

Why Transformer Shortages Are Stalling AI Data Centers
Moratorium bills, grid bottlenecks, and community pushback are turning announced data center capacity into a much murkier real-world timeline.
BusinessIn April 2026, the Maine State Legislature passed a moratorium1 bill that would temporarily restrict new data centers above a certain size. But on April 24, Governor Janet Mills vetoed it, citing the absence of an exception for a specific regional project. Passing a legislature and taking effect as law are two different things.
State Senator Melanie Sachs, who sponsored the bill, said she initially thought, “Maine isn’t even a candidate site for data centers, so would anyone even react?” It was only after introducing the bill that she learned two large data center projects were already moving into her own state — and the bill went on to pass the legislature.
“Data center opposition halted or delayed ₩200 trillion (~$144B) worth of construction in Q1 alone”Data center opposition halted or delayed ₩200 trillion (~$144B) worth of construction in the first quarter of this year alone.Discussions about restricting data center construction are continuing in other regions too. Sightline Climate has suggested that a significant share of projects slated to come online in 2026 could face delays, and moratorium bills have been introduced in multiple US states. Still, introduction, passage, and enforcement remain distinct stages.
“Halt data center construction”… A signal flare for full-scale AI regulation battles in US politicsAs conflict over artificial intelligence (AI) regulation intensifies in American politics, Senator Bernie Sanders (Independent, Vermont) has introduced a bill to fully halt new data center construction until AI regulations are established…Even with capital and chips secured, a facility can’t go online if the power equipment, grid interconnection, and permitting aren’t ready. The reasons for delay differ from project to project, but securing power has emerged as a critical condition.
What I find notable is that long construction timelines leave room for the very way AI is used to change in the meantime. We need to examine how flexibly power, cooling, and equipment configurations can be adjusted once both training and inference2 demand are factored in together.
The Gap Between Announced Investment and Actual Operation
Even as big tech companies’ capital expenditures rise, not all of that money goes toward data center buildings or AI training facilities alone. We need to separate investment plans — which include equipment, servers, and networking — from actual completion and operational capacity.
Sightline Climate3 has found a wide gap between data center project announcements and actual construction progress. Reading all the power capacity (GW)4 included in construction plans as capacity that will actually go live that same year risks overestimating demand.
Schedule delays alone aren’t enough to conclude that AI demand has disappeared. I think we need to look beyond funding and customer demand to the state of transformer procurement, transmission grid expansion, and permitting.
These power constraints can affect not just training facilities but also facilities handling inference and general cloud workloads. We shouldn’t assume, without evidence, that most delayed projects are for training and narrow a facility’s purpose on that basis alone.
Let’s look at how transformers, the power grid, and community concerns are affecting construction timelines.
🔌 Some large transformers take years to deliver
Wood Mackenzie explained that the average lead time for large generator step-up and power transformers runs to about 3 years, with some cases observed at 4-5 years. Specs, timing, and manufacturer all cause significant variation, and not every transformer faces the same lead time.
A transformer is equipment that converts high-voltage electricity into the voltage a data center can actually use. Without one, there’s simply no way to draw power from a plant. So why has this shortage suddenly become so acute?
Large power transformers require project-specific design, skilled labor, and manufacturing and testing facilities. They also need materials like grain-oriented electrical steel5 and copper. Wood Mackenzie’s August 2025 analysis estimated the annual demand-supply shortfall for power transformers in the US at roughly 30%. That doesn’t mean supply is nonexistent.
The same analysis estimated that about 80% of US power transformer supply and about 50% of distribution transformer supply come from imports. It found that demand for generator step-up transformers had grown 274% compared to 2019. Since supply, demand, and lead times6 vary by transformer type, it’s hard to capture the whole picture with a single ratio.
Against this backdrop, the World Resources Institute (WRI) found that power infrastructure shortages are extending data center construction timelines by 24-72 months. This reflects delay cases for projects facing power constraints—it doesn’t represent the minimum construction time for every data center.
When a supply shortage drags on, companies gain an incentive to order more than they actually need just to lock in delivery dates. That’s why concerns arise about a bullwhip effect7—where order fluctuations get amplified up the supply chain. Still, order volumes, warehouse inventory, and actual installations need to be checked separately.
⚡ Local Residents Have Become a Variable in AI Infrastructure
The cost and quality-of-life concerns residents raise matter too.
The Maine debate mentioned earlier is a case in point. Behind the surprisingly fast passage of the anti-data-center bill in the Maine legislature was a sentiment captured bluntly by state representative Amy Roeder’s remarks: “Residents are dying under monthly electricity bills of hundreds of dollars. Siting a resource-hungry data center on top of that feels irresponsible.”
This isn’t just a Maine story. As of early 2026, data center moratorium bills have been introduced in at least 12 states — Virginia, Michigan, Wisconsin, New York, Ohio, Louisiana, and others. One especially symbolic case happened in Festus, Missouri. Anti-data-center sentiment erupted so forcefully that half of the eight city council members were voted out. Ohio residents are pushing a ballot initiative to permanently ban large data centers outright, and in Michigan, resident opposition sank a $1 billion project reportedly tied to Meta.
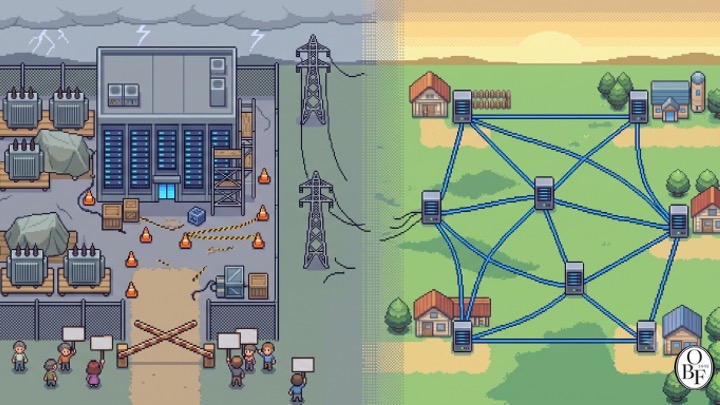
Olivia Wang, an analyst at Sightline Climate, put it this way: “Community pushback has become a real driver of project attrition now.” In other words, it’s no longer a side variable — it’s central.
Large data centers require a lot of power, but the exact scale varies with facility and campus design. The contested question is how the cost of expanding the grid to meet new demand should be split between data centers and other ratepayers. In some cases, rates and contracts are structured so that large users bear the cost themselves, so it’s not a given that residential bills will rise.
But there’s a risk: if the grid is expanded in anticipation of demand and a project is then canceled or exits early, other consumers could be left holding the bill. WRI points to long-term contracts, minimum payment clauses, and separate rate classes as tools to reduce this risk. Water use, noise, and local jobs are also on the table for discussion.
⚙️ Power Demand Overlaps With the Steel Industry, Too
Residents aren’t the only ones competing with data centers for electricity. The steel industry needs the same power in massive quantities. And steel happens to be a core material that goes into building data centers in the first place.
A report released last week by the Steel Manufacturers Association (SMA) in the US raised concerns about electricity costs. It found that rising power demand from data centers is pushing up steel companies’ electricity bills by tens of millions of dollars a year. The SMA warned that having to compete for the same electricity as data centers—now the industry’s largest new customers—poses a major risk to steel producers.
Why is steel so sensitive to electricity? About 70% of steel produced in the US is made using the electric arc furnace (EAF)8** method, which melts scrap metal with electricity to produce new steel. A single plant running this way uses an enormous amount of power. So when a data center moves into the same region and starts drawing heavily on the grid, it can affect steel plants’ production costs, depending on power supply and rate contracts.**
Data center construction requires steel, and steel production requires electricity. When demand from both industries grows in the same region, it can strain both power supply and pricing. It’s worth keeping in mind that capacity expansion in one industry can ripple into costs for a related industry.
🏭 Even self-generated power has costs and supply conditions
So couldn’t data center companies just build their own power plants? Some are actually doing this — installing natural gas turbine generators on-site.
Self-generation still requires procuring gas turbines, securing fuel contracts, obtaining permits, and managing emissions. Natural gas prices vary by region and contract, and they’re also affected by geopolitical conditions. You have to weigh the cost of waiting for the grid against the construction and operating costs of self-generation.
There’s a more serious problem here. I noticed a case I read about in an article. Near Nvidia’s headquarters in Santa Clara, there are two already-completed data centers. The servers are fully installed. But the local utility can’t provide an electrical connection, so they’re sitting completely offline, unused. The buildings exist, but they can’t open because there’s no power.
Future power demand also carries a lot of uncertainty. Forecasts point to substantial demand growth, and in some regions, the queue for new large-load connections stretches out 5 to 7 years.
When reviewing a project, you need to check not just capital, chips, and site availability, but also transformers, transmission networks, generation capacity, and local permitting. Understanding what’s actually blocking operations is essential to judging the length of delays and their costs.
Manufacturing equipment and expanding the grid require not just technical capability but also permits and investment decisions. This is why semiconductor product release cycles alone can’t explain data center operational timelines.
If electricity rates rise, the operating economics of power-inefficient GPUs can worsen. That said, this doesn’t automatically mean accounting depreciation periods get shortened or that new GPUs suddenly become useless. You have to calculate utilization, processing performance, revenue, and power costs together.
During long lead times, the workloads to be processed and the equipment configuration can also change. What matters is how well the power and cooling infrastructure is designed to adapt to future, varied use cases.
Oswarld’s Lens
AI data centers need to be designed with both training and inference workloads in mind. Power density per rack9 and networking requirements vary depending on model size, throughput, and latency targets.
Deloitte projects that inference’s share of total AI compute will grow from roughly one-third in 2023 to roughly two-thirds by 2026. The same report also expects continued growth in demand for high-performance GPUs, HBM, and large-scale data centers. A rising share of inference doesn’t mean GPUs are being replaced by CPUs.
Agents require more than just model inference — they also need tool execution, data retrieval, and state management. CPUs and DDR5 server DRAM10 play a role in this process, but GPUs and other accelerators remain critical for inferring large models. Which combination makes sense should be judged by measuring performance and cost for each specific workload.
In shaping go-to-market strategy, I’ve repeatedly seen that as a market grows, operational efficiency starts to matter just as much as peak performance. Given how long data centers take to build, I think operators need to model actual customer training and inference demand and power costs under multiple scenarios. Rather than assuming a training facility will become obsolete by the time it’s completed, it makes more sense to check whether it retains the flexibility to handle different kinds of workloads.
Closing looks fine as a section name per glossary. Let me verify against the glossary mapping: Closing → Closing. Good, matches.
Closing
Transformer procurement, grid interconnection, and local community acceptance are critical constraints on AI data centers. Capital and chip supply alone aren’t enough to judge whether an investment plan is actually feasible.
How long resolution takes varies by region, equipment, and project status. In some cases, expanding manufacturing capacity and securing power contracts and permits has taken years.
Even as inference workloads grow, demand for GPUs and large data centers isn’t about to disappear. We need to weigh the roles of CPUs, memory, and accelerators—and their power efficiency—against actual workloads.
Understanding AI infrastructure requires looking beyond chipmakers’ earnings to equipment lead times, power contracts, permitting, and real-world utilization rates.
Every week, I put together a newsletter that cuts across technology, economics, and the humanities. If it struck you as unexpected that steel mills and data centers are competing for the same electricity, I’d love to know how power demand from data centers is being felt in your own industry—whether through electricity rates, component sourcing, or some entirely different channel.
📨 If you know someone who’d find this useful, please share it with them.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- Sightline Climate, Data Center Outlook: Half of 2026 Pipeline May Not Materialize, February 2026. : This is the primary source tracking actual construction progress across the 2026 data center pipeline. It’s the core evidence behind this issue.
- Catherine Boudreau, “Up to half of the world’s data centers may be delayed this year”, Latitude Media, February 2026. : The most thorough breakdown of the Sightline report I’ve found.
- Ian Goldsmith & Zach Byrum, “Powering the US Data Center Boom: The Challenge of Forecasting Electricity Needs”, World Resources Institute, September 2025. : A structural rundown of the uncertainty in electricity demand forecasting and the “phantom load” problem.
- McKinsey & Company, The next big shifts in AI workloads and hyperscaler strategies, December 2025. : The most compelling piece I’ve read on the infrastructure implications of the shift from training to inference. This is the core evidence behind today’s “Oswarld’s Lens” section.
- Deloitte, Why AI’s next phase will likely demand more computational power, not less, 2026 TMT Predictions. : The source behind the forecasts on inference workload share.
- The Wall Street Journal, “AI Data Centers Have Been Great for the Steel Industry. Now, a Power Crisis Looms.”, 2026. : Covers the competition for electricity between the steel industry and data centers. Citing a report from the Steel Manufacturers Association (SMA), it examines the cost impact across related industries. (Paywalled)
Background
-
Office of the Governor of Maine, Governor Mills Announces Decision on LD 307, 4/24/2026. : Notice of the veto of a bill that had passed the legislature.
-
Wood Mackenzie, Transformer troubles, 8/13/2025. : Breaks down supply and import dependence by transformer type.
-
POWER Magazine, “Transformers in 2026: Shortage, Scramble, or Self-Inflicted Crisis?”, January 2026. : A detailed industry-perspective dissection of the causes behind the transformer supply chain crisis.
-
CNN, “Data centers are spreading around the country. Now, data-center bans are, too”, April 2026. : Lays out the background of the Maine moratorium case well. This is the source for this issue’s opening.
-
Ed Zitron, Where’s Your Ed At newsletter : The critic who was first to spotlight the Sightline Climate data. Lays out a systematic case for skepticism toward the AI bubble.
Footnotes
-
Moratorium: A system that fully suspends a specific activity or project for a set period. Here, it refers to a measure banning new data center construction for a defined period. ↩
-
Training vs. inference: Training is the stage where an AI model is first built, requiring repeated processing of enormous amounts of data and consuming huge amounts of power. Inference is the stage where a completed model answers a user’s query each time it’s asked—each individual computation is far lighter, but the total load grows large as the number of users increases. ↩
-
Sightline Climate: A US climate and energy technology market intelligence firm. It tracks the actual construction progress of data center projects through on-site verification. Its “Data Center Outlook” report, published in February 2026, has become a major reference point for the industry. ↩
-
Gigawatt (GW): A unit of power capacity. 1GW equals 1,000MW. Converting capacity into number of households requires assumptions about average usage and utilization rates. A single large nuclear power plant produces roughly 1–1.4GW. ↩
-
Grain-Oriented Electrical Steel: A specialty steel sheet used in transformer cores. Its low magnetic loss has a decisive effect on transformer efficiency. Only a handful of companies worldwide are capable of producing it. ↩
-
Transformer lead time: The time it takes from ordering a transformer to receiving it. This used to run a few months, but as of 2025, large power transformers typically take 24 to 48 months. ↩
-
Bullwhip effect: Just as a whip’s motion amplifies toward its tip, order-quantity fluctuations amplify as you move upstream in a supply chain. Orders that overshoot actual demand can accumulate, eventually leading to excess inventory or a sudden demand cliff. ↩
-
Electric arc furnace (EAF): A method of making new steel by melting scrap metal with the heat of an electric arc. It emits less carbon than coal-fired blast furnaces but relies more heavily on electricity. About 70% of US steel production uses this method, making it especially sensitive to electricity prices. ↩
-
Power density per rack (kW per rack): The amount of power a single server rack in a data center uses. A typical server rack draws around 10kW, while AI training racks draw 100–160kW, and next-generation systems can reach 1MW (1,000kW). The higher the density, the harder the cooling challenge. ↩
-
DDR5 server DRAM: The latest generation of standard server memory. Whereas HBM (High Bandwidth Memory) is premium memory that sits right next to the GPU, DDR5 is general-purpose server memory used alongside the CPU. Demand for it is surging as inference workloads grow. ↩
Related issues
Meta Weighs Selling Its Spare AI Cloud Capacity
Bloomberg reports Meta may rent out surplus AI computing power to outside customers for the first time.
BusinessThe 'AI Screens Resumes' Claim Traces to a Game-Based Tool
A study of 4.2 million job applications was about a game-based hiring tool—not resume-screening AI in general.
Business
Amazon Cuts 30,000 Jobs While Hiring Interns, Grads
Layoffs and entry-level hiring aren't contradictory at Amazon—an internal AI-usage race exposes what's really being measured.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?