Battery Recyclers Ran on Factory Scrap, Not Scrapped EVs
Utilization was set by battery factories, not EVs on the road — and that link starts breaking in 2026
BusinessCapacity Was 1.2 Million Tons, But Only 440,000 Tons of Feedstock Showed Up
Battery recycling has been one of the most frequently pitched growth industries of the past few years — and, at the same time, one of the biggest money-losers. Line up the numbers and the reason becomes obvious. As of 2023, global recycling capacity stood at roughly 1.2 million tons for pre-processing1 and about 1.25 million tons for post-processing, but the combined supply of end-of-life batteries and manufacturing scrap2 available to feed that capacity totaled only around 440,000 tons. In other words, there was only enough feedstock to fill about a third of the installed capacity.
Over the same period, market forecasts kept getting bigger. The estimate that feedstock volume would reach 6.2 million tons by 2040 remained fully intact. So the growth outlook and the weak utilization weren’t actually contradicting each other. One was a number for 2040; the other was the number of trucks currently pulling up to the factory gate.
Utilization Was Decided Inside the Factory, Not Out on the Road
Yet what recycling plants are actually feeding into their machines right now rarely makes it into the coverage.
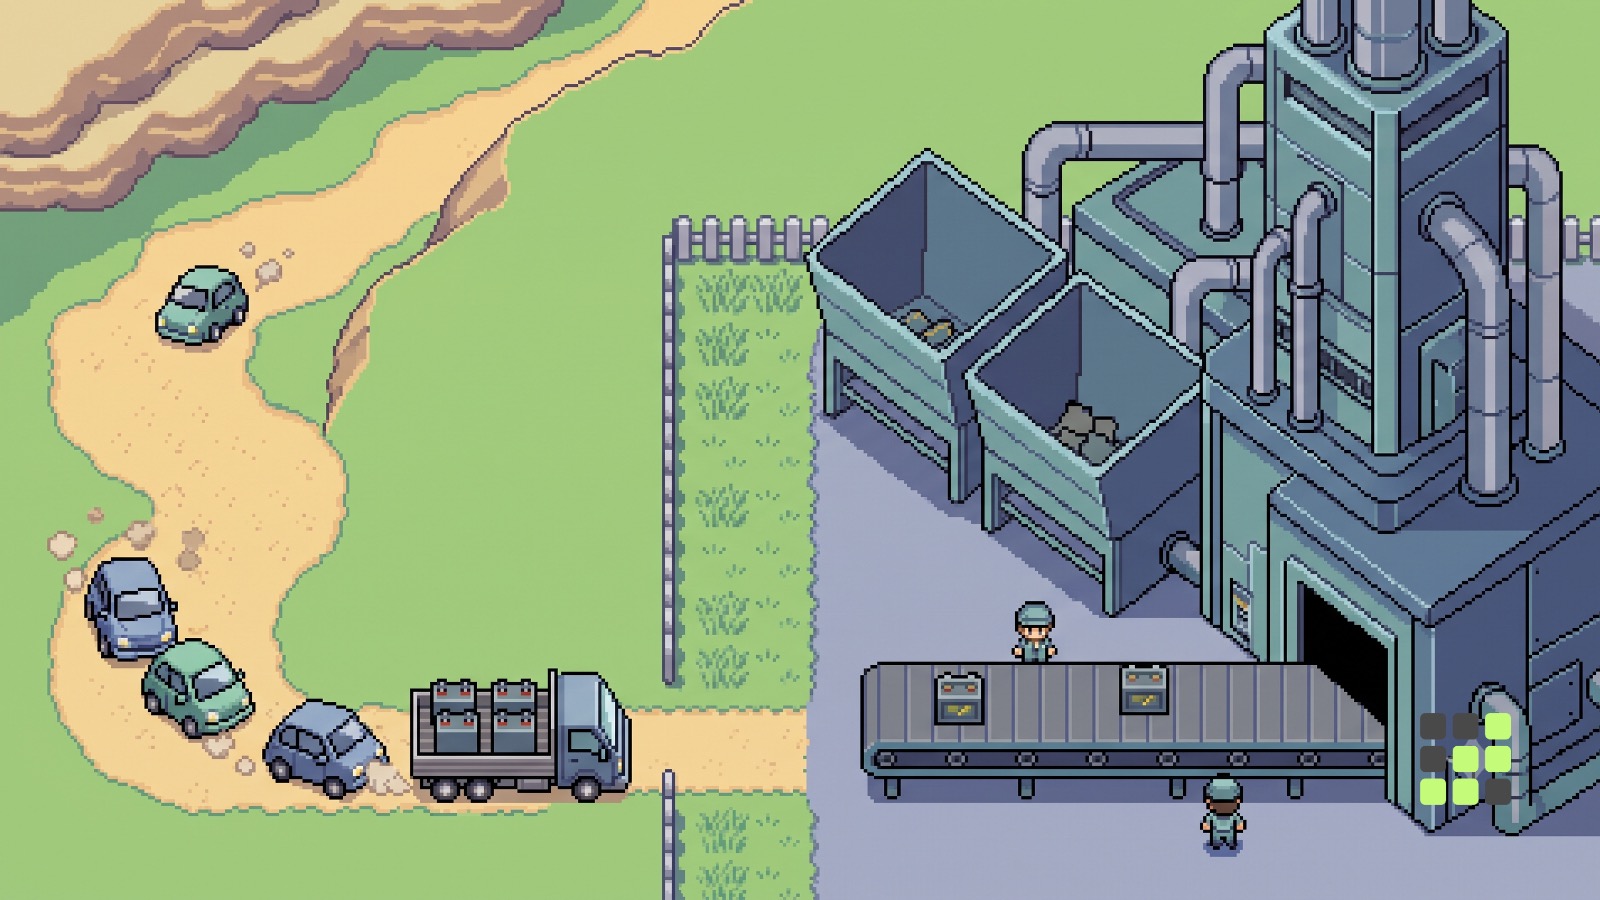
Through 2025, the primary feedstock for Korean recyclers wasn’t end-of-life batteries pulled out of retired cars. It was scrap — the defective units and process byproducts coming out of battery cell and cathode material plants. End-of-life batteries split between reuse and recycling, but manufacturing scrap goes almost entirely into recycling. Because the volume was steady and the composition uniform, it was the easiest feedstock for an early-stage recycling business to handle.
But this feedstock has one inconvenient trait. Scrap doesn’t appear when batteries sell well — it appears when batteries get made. When EV demand slowed and battery makers halted production lines, defective units shrank right along with it. Recycling capacity wasn’t a buffer against the EV market; it was a downstream process that simply inherited the battery factories’ utilization rate.
This is exactly where the industry’s narrative and its reality diverged. Investor decks explained the sector in terms of the number of EVs on the road, but the income statement moved with battery factories’ production schedules. Capacity-expansion decisions were made by watching the front clock; feedstock supply followed the back clock.
On top of that came selling prices. Recyclers buy scrap and end-of-life batteries, extract lithium, nickel, and cobalt, and resell them, so the metal price they extract is essentially their selling price. Lithium carbonate broke below ¥100 (RMB) per kilogram in November 2023 and stayed depressed for a long time, while nickel also lingered at low levels. Because feedstock purchase prices lag the market, margins are the first thing to shrink when selling prices fall. SungEel HiTech posted revenue of ₩247.4 billion (~$178M) and an operating loss of ₩8.3 billion (~$6M) in 2023. The more a company had expanded its capacity, the faster its fixed costs piled up.
2026 Is the Year Feedstock Origins Change
This structure is now shifting. Analysts have long pegged 2026 as the point where end-of-life battery volume overtakes cell-scrap volume, because that’s when the early wave of EVs sold years ago starts reaching the end of its life in earnest. That means feedstock origins move from inside the factory to out on the road — and from that point on, the recycling industry’s utilization tracks not battery factories’ production plans, but sales volumes and scrappage counts from a decade earlier.
Ground-level indicators are turning as well. SungEel HiTech idled its older Plants 1 and 2 starting in 2023 and concentrated operations at its more efficient Plant 3 in Saemangeum, a reclaimed industrial zone in South Korea. As of April 2026, Plant 3’s utilization reportedly reached about 90%, and the company was said to be doubling Plant 2’s capacity and restarting it in May. Its feedstock supplier network also expanded from roughly 30 sources to 100. Brokerage estimates put Plant 3’s utilization rising from 70–80% in Q4 2025 to near 100% in Q3 2026.
Metal prices have also passed their bottom. Cobalt rose from $33,406 per ton in September 2025 to $55,854 in June 2026; nickel rose from $15,275 per ton in February 2025 to $17,664 in June 2026. Lithium climbed from $16 per kilogram in January 2026 to $24.1 in May before correcting back to $21.6. With selling prices climbing and new-plant utilization rising in step, forecasts have emerged that Korean recyclers will cross quarterly breakeven sometime in 2026. Nickel, however, stood at $16,755 per ton as of September 8, 2026 — lower than in June — so it’s hard to say the recovery is running in only one direction.
Policy has moved the same way. The Act on the Management of Used Batteries and the Promotion of the Industry was promulgated on May 26, 2026, and takes effect May 27, 2027. It classifies end-of-life batteries as an industrial resource rather than waste, and lays the legal groundwork for pre-removal performance testing, a full lifecycle tracking-and-trading system, and a recycled-content certification scheme. Government projections show domestic end-of-life battery volume growing from 8,321 units in 2025 to about 107,500 units by 2030. Once collection routes and traceability are codified in law, feedstock that used to be scraped together through individual contracts starts flowing through an institutionalized distribution network.
Search Interest Left Before Earnings Did
What’s interesting is that public attention moved in the opposite direction. In our own search-trend analysis, monthly search volume for the keyword used batteries came in at 17,840 in July 2026, on a declining trend, at 0.791 times the volume of the comparison period. Attention peaked not during the deepest stretch of losses, but earlier, during the phase of anticipation — and by the time earnings turned the corner, interest had already drained away.
A clear line needs to be drawn here. Search volume is just search volume — it’s not evidence of market size, adoption, or investment performance. A drop in searches doesn’t mean the industry is dying, and a rise doesn’t mean demand has materialized. But one thing can be read from it: searches on this topic have tracked closer to questions about which stocks to buy than questions about understanding the industry’s structure, and when the stock narrative cools, the questions cool with it — even though right now, as the feedstock structure changes, is the first moment this industry can actually be seen clearly.
Oswarld’s Lens
When I look at this industry, I try to see three things differently.
First, the leading indicator needs to change. Battery-recycling coverage has always started with EV sales figures, but what actually drove profit and loss through 2025 was the utilization rate at battery cell and cathode plants. From 2026 onward, scrapped-vehicle registrations and battery removal counts get added to that mix. Without knowing what share of feedstock comes from which source, you can’t forecast a company’s next quarter.
Second, in this industry capacity size isn’t a competitiveness indicator. The number of feedstock supply contracts is. I’d argue that SungEel HiTech expanding its supplier network from about 30 sources to 100 matters more than any capacity-expansion announcement. In a feedstock-scarce industry, capacity is a fixed cost, and the procurement network is the asset.
Third, the floor for demand gets built by regulation, not by market prices. The EU has been phasing in carbon rules for battery manufacturing and minimum recycled-content requirements, and Korea has written a recycled-content certification scheme into law. Once a market emerges where you can’t sell without using recycled metal, the price of recycled metal starts moving independently of mined-metal prices. Whether that decoupling actually happens is the fork in the road that determines this industry’s long-term profitability.
 Closing
The fact that a growing outlook and weak utilization coexisted in the used-battery market wasn’t because someone inflated the numbers. It’s because capacity was built on the clock of battery production, while feedstock arrived on the clock of automobile lifespans. The gap between those two clocks produced nearly three years of losses.
2026 is the stretch where that gap first starts to narrow. But even now, what I’ll watch first isn’t the forecast — it’s what share of feedstock comes from end-of-life batteries, how many procurement contracts exist, and whether recycled-content mandates actually translate into purchases. Metal prices are far more volatile than any of that, and their direction hasn’t settled one way yet.
💬 Does your industry have indicators where the forecast clock and the actual-volume clock run out of sync? Let me know in the comments which numbers you watch first.
📨 If you think this piece could help a colleague in batteries, materials, or resource circulation who’s wrestling with feedstock sourcing, go ahead and forward it to them.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- SK Ecoplant Newsroom, “Is Half of Global Battery Recycling Capacity Sitting Idle? How to Secure a Stable Supply of Used Batteries”, March 2024. ··· Compares installed capacity against feedstock volume, in tons
- Law Times, “Key Provisions and Implications of the Used Battery Act”, June 2026. ··· Lays out the promulgation and effective dates, and the structure of performance evaluation, lifecycle tracking, and recycled-content certification
- Korea Economic TV, “SungEel HiTech to Restart Plant Next Month”, April 8, 2026. ··· Reporting on Plant 3’s utilization rate and expanded feedstock sourcing
- Digital Today, “Lithium Price Climbs From $8 to $22, Putting Battery Recyclers’ Profit Turnaround Within Sight”, August 7, 2026. ··· Explains the link between metal prices and recyclers’ P&L
Background
- The Elec, “SungEel HiTech’s Plant 3 to Begin Operating in June”, March 2024. ··· An article confirming 2023 earnings and the impact of falling metal prices
- SNE Research, “Global Used Battery Recycling Market Outlook”. ··· A starting point for distinguishing used batteries from scrap as separate market segments
- Kim & Chang, “Legal, Institutional, and Infrastructure Measures for Fostering the Used Battery Industry”. ··· Context on excluding black powder from waste regulation and the institutional background of the recycled-content certification scheme
📝 Glossary
Footnotes
-
Pre-processing and post-processing: Pre-processing discharges, disassembles, heat-treats, and shreds batteries into a powdered intermediate product. Post-processing then uses wet smelting (hydrometallurgy) on that powder to extract materials like nickel, cobalt, and lithium. ↩
-
Scrap: The defective units and byproducts generated while manufacturing battery cells or cathode materials. Unlike end-of-life batteries, scrap is generated at the manufacturing stage, and because its composition is uniform, virtually all of it goes into recycling. ↩
Related issues
We Found 10GW More Power, Yet the Shortfall Grew by 19GW
The gap isn't from more data centers—it's from how much power a single AI server rack now needs
BusinessForeign Caregiver Pilot Got Pricier, Not Cheaper
It started with 100 workers and ended with 73, while hourly rates jumped 36% in two years.
BusinessNo-Show Fees Hit 40%—Only 14% of Restaurants Collect Deposits
Korea raised the no-show penalty cap to 40%, but most restaurants still can't legally charge it.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?