

Korea's AI Rankings Hide a Talent Problem
South Korea ranks high in AI models and patents per capita, but struggles to retain research talent and scale industrial results.
SocietyUsing AI a Lot Isn’t the Same as Having a Competitive AI Industry
MIT Technology Review ran Michelle Kim’s piece, “Why Do South Koreans Love AI So Much?”, on June 15, 2026. It’s a story about why Koreans have embraced AI so readily.
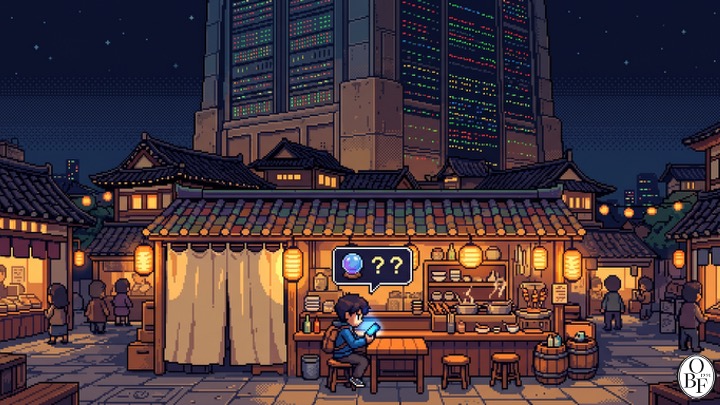
The article opens with a scene of the reporter’s cousin asking ChatGPT for her saju, a Korean fortune-telling reading based on one’s birth date and time, at a pocha, a street-side tented bar, in Seoul’s Jungang Market. The cousin, a 29-year-old insurance agent, also asks the chatbot for advice on dating and investing. Citing a Gallup Korea survey, the article notes that 46% of people in their twenties have used a chatbot to check their fortune. AI has become an everyday conversation partner. But that alone doesn’t tell us whether Korea’s AI use is merely superficial, nor does it tell us how competitive the country’s AI industry actually is.
Starting from this article, I wanted to take a separate look at Korea’s AI competitiveness. How much people like AI, how well companies perform at building models, and how well the country secures research talent are three different questions. Even the government’s “AI G3” goal only makes sense once you ask: third place by which measure, exactly?
AI Optimism and Job Anxiety
In Pew Research Center’s 2025 survey across 25 countries, South Korea recorded the lowest share of respondents saying they were more concerned than excited about AI, at just 16%. The US and Italy each came in at 50%, and Australia at 49%. That doesn’t mean the remaining 84% of Korean respondents are all optimistic — the figure also includes those who said their excitement and concern were roughly balanced.
Korea’s growth trajectory, built on steel, semiconductors, and telecommunications technology, may help explain this optimism. In an interview with MIT Technology Review, KAIST Professor Chihyung Jeon noted that the government has consistently framed AI as a technology for a better future.
The government set its 2026 AI-related budget at ₩9.9 trillion (~$7.1 billion). It is pursuing GPU procurement and building a national AI computing center, while also running a program to develop its own foundation model1. The policy channels funding into research infrastructure and model development to grow the AI industry.
An Ipsos-Google survey featured in Stanford’s AI Index 2026 found that 70% of Korean respondents prioritized promoting AI innovation in fields like science and healthcare over protecting existing industries affected by AI through regulation. The question wasn’t about opposing all regulation aimed at safety or privacy.
This optimism doesn’t erase anxiety about employment. The same article cites the case of Hyundai Motor’s plan to introduce Atlas robots at its factory, which drew pushback from the union demanding a labor-management agreement. Finding AI convenient and worrying about what it might do to your own job can coexist.
Model counts, patent counts, and performance are three different things
In AI Index 2026, Korea ranks near the top on both model-development and patent metrics. But these two indicators measure different things.
In 2025, the number of “notable AI models” released was 59 for the United States, 35 for China, and 8 for Korea. By this tally, Korea ranks third in the world. This is a count of models the report selected as notable — not a total count of every model each country produced, and not a ranking of model performance.
In 2024, Korea had the highest number of registered AI patents per 100,000 people, at 14.31. That means Korea’s patent-registration record is strong relative to its population. It shouldn’t be read more broadly as meaning Korea ranks first in the world in total patent count, commercial value, or AI model performance.
Comparing the performance of individual models requires using the same point in time and the same evaluation criteria. LG AI Research announced that in January 2026, K-EXAONE ranked 7th in the world among open-weight models on the Artificial Analysis Intelligence Index2. That’s an achievement measured among publicly released models. It wouldn’t be appropriate to place this score alongside an index score from a different point in time and calculate that “Korean models perform 40% worse.” The test items, the index version, and the models being compared all need to match — and a gap in scores doesn’t directly translate into a proportional gap in capability, either.
It’s also hard to lump all domestic models together as similarly sized “small” models. K-EXAONE, for instance, has 236 billion total parameters, of which roughly 23 billion are activated when processing an input. Since models differ in scale, design, and how openly they’re released, comparisons with frontier models3 from the US and China need to account for concrete task performance and operating costs together.
There’s a point I always make at seminars or discussions on sovereign AI. Sovereign AI needs to be understood as covering not just the ability to build models, but the ability to secure the necessary data and compute, and to run services independently. Achievements in selling a model alone don’t establish control over the supply chain or over operations.
On distillation — using another model’s outputs for training — I don’t think the method itself is the problem. What matters is under what authority, using what data, and to what end. Because terms of service and licensing have to be checked case by case, you can’t blanket-state that “distillation carries no legal risk.” And the fact that a model was trained from scratch4 doesn’t, by itself, prove anything about its performance or operational capability either.
Then there’s the challenge of retaining research talent. In AI Index 2025, Korea’s net AI talent migration rate for 2024 was -0.36 per 10,000 LinkedIn members. This figure is calculated based on profile movements among LinkedIn members, not the population as a whole. The Bank of Korea presented this as ranking Korea 35th out of 38 OECD countries. That means more AI talent left than entered, according to this data — it does not mean Korean AI talent ranks 35th in skill.
In the Bank of Korea’s 2025 survey of STEM workers, 42.9% of respondents currently working in Korea said they were considering moving abroad within the next three years. Compensation wasn’t the only reason cited — research environment and career opportunities came up too. Rather than explaining talent outflow with a single cause by naively comparing Korean and US PhD salaries — figures tallied under very different conditions — we should also examine the conditions needed to sustain research careers domestically.
A strong patent-registration record and a net outflow of talent can both be true at the same time. Patent counts don’t tell you whether the researchers behind them will keep working domestically going forward. I think building up development achievements and retaining the people who produced them need to be managed as two separate problems.
The Challenge of Turning Domestic Success into Global Competitiveness
Korea’s internet service history is worth revisiting here. Launching early or building a large domestic user base didn’t automatically translate into success abroad.
Cyworld launched its service in 1999, and its “minihompy” personal homepages and avatars later became hugely popular domestically. Naver Knowledge iN started in 2002, collecting user questions and answers before Yahoo Answers did. Korea was a market where broadband penetration and online service adoption moved fast.
But Cyworld struggled with overseas expansion and the transition to mobile, and Naver’s dominance in domestic search never translated into global search market share. The practice of implementing security and authentication requirements for electronic banking through ActiveX deepened dependence on Internet Explorer. It would be inaccurate to say the government legally mandated ActiveX itself, but it’s worth reflecting on how regulation and implementation choices combined to lock the country into a single technology for years.
You can’t reduce these cases to one single cause. But there’s a common thread worth examining: technology or services that work well domestically can become constraints when they meet foreign usage environments, different browsers, or new devices. This mismatch—where technology tailored only to domestic conditions fails to be compatible with outside markets—is sometimes called the “Galápagos syndrome”5.
In AI, how to evaluate “independent development” has become a point of debate. In January 2026, Naver Cloud was eliminated in the first round of evaluation for the government’s independent AI foundation model project. According to the Ministry of Science and ICT’s explanation, the point of contention was that Naver Cloud had used an external model’s vision and speech encoder weights without modification, keeping them frozen. The government judged this as failing to meet the project’s standard for independence. This wasn’t a case of confirmed license violation, nor a ruling that Naver’s entire language model was a fine-tune6 of a foreign model.
LG AI Research, SK Telecom, and Upstage were selected to move to the next stage at the time. Looking at this outcome, I feel the government needs to more clearly explain the purpose behind the independence it’s asking for. Whether the standard is “can a company improve and operate the technology on its own, even while using external components” or “priority goes to training every component’s weights from scratch”—the answer determines which direction companies invest in. I can’t flatly conclude this policy will produce an ActiveX-style outcome, but we still need to keep testing whether these evaluation criteria actually help real competitiveness.
Strengths Built in Semiconductors and Industrial Settings
We also need to look concretely at how AI can be applied to fields where Korea already excels.
Samsung Electronics and SK Hynix are major suppliers of high-bandwidth memory (HBM)7, used in AI servers. US-based Micron also competes in this market. That Korean companies supply critical components is clearly a strength, but it doesn’t mean they monopolize or control the entire AI semiconductor supply chain.
Users who eagerly try out new technology are also an asset. A MIT Technology Review article covers a range of domestic use cases, from chatbots to care robots to AI-equipped bus stops. This kind of environment can serve as a testbed8 for actually trialing AI services. But to gauge the real value, we need to look not just at adoption numbers but at what users actually gained.
I’m focused on how semiconductor supply and rapid adoption translate into competitiveness for domestic services. A country can supply HBM well while service revenue still flows to foreign companies. Domestic firms might also use foreign AI to boost their own productivity and product quality. Either way, we need to look concretely at exactly what technology and revenue actually accumulate domestically.
The investment required to develop general-purpose models is enormous. According to AI Index 2026, US private AI investment in 2025 totaled $285.9 billion. This can’t be compared as a straightforward multiple against Korea’s 2026 government AI budget — the years differ, and so does the scope (private versus government). I believe that when allocating limited resources, more weight should go toward applying AI in areas where domestic companies already have field expertise and customers — semiconductor process optimization, battery quality control, content production.
Oswarld’s Lens
I think the way Korea calls itself an “AI G3” is a risky habit.
I’ve run into this problem repeatedly while building GTM strategies: fixating on “where we rank” can blur your judgment about what to actually deliver to which customer. The fact that Korea ranks third in the number of notable models is a real achievement, but a headcount of 59 U.S. models versus 8 Korean models doesn’t mean the two countries’ industrial competitiveness sits at the same level. You also have to look at revenue, users, research talent, and operational infrastructure — none of which shows up in a model count.
What interests me more is the differentiation domestic AI companies are pushing: Korean-language performance and cost efficiency. A strategy of focusing on specific customers and tasks is perfectly valid. But it needs to explain what market that strategy is meant to capture, and how that connects to the national goal of being “G3.” Winning customers for a specific task and competing for the lead in general-purpose models require different investment and different go-to-market approaches.
I think Korea needs a much clearer set of priorities around putting AI to work on the industrial floor. Model development and applied services both matter, but you can’t fund every front with equal intensity. You need to be specific about what to build in-house, what to source externally, and what domestic companies’ hands-on field experience should be turned into as a product. Pride in a ranking shouldn’t become an excuse to keep postponing those choices.
Closing
Korea has what it needs on paper: users who embrace AI readily, government investment, and the supply capacity of its semiconductor companies. What remains is to build on that foundation—improving conditions for research talent and translating this into actual results, industry by industry.
Rather than dwelling on the phrase “third in AI,” I think we should first ask what problems can actually be solved, and whether there are people and operational infrastructure in place to keep doing that work.
For the insurance agent mentioned in the article, what mattered wasn’t the country’s model rankings—it was whether the chatbot was useful right now. I hope industrial policy doesn’t lose sight of checking the actual impact on real users and businesses.
💬 Which areas of domestic industry do you think should be prioritized for AI adoption? Let us know in the comments.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- Michelle Kim, 「Why Do South Koreans Love AI So Much?」, MIT Technology Review, 2026.06.15. A piece on how Koreans use and perceive AI.
- Stanford HAI, AI Index Report 2026. Models and patents are covered in Chapter 1, investment and employment in Chapter 4, and public-perception surveys in Chapter 9.
- Stanford HAI, AI Index Report 2025, Chapter 4, Figure 4.2.23. Net migration figures for AI talent based on LinkedIn membership data in 2024.
- Pew Research Center, 「How People Around the World View AI」, 2025.10.15. A survey of AI perceptions across 25 countries.
- Bank of Korea, 「Determinants of Overseas Outflow of STEM Talent and Policy Responses」, 2025.11.03. A report covering workforce-mobility indicators and surveys of STEM talent both in Korea and abroad.
Background
- LG AI Research, K-EXAONE Global Evaluation and Model Overview, 2026.01.12. Explains the model’s scale and its ranking among open-weight models at the time.
- Ministry of Science and ICT, Briefing on First-Stage Evaluation Results for Domestically Developed AI Foundation Models, 2026.01.15. The official explanation of the “domestic originality” criteria and the controversy over the Naver Cloud evaluation.
- Ministry of Agriculture, Food and Rural Affairs, 38 Key Achievements of the People’s Sovereign Government, 2026.05. A government document covering the 2026 AI investment budget and model-development results.
Footnotes
-
Foundation Model: A general-purpose AI model pre-trained on massive datasets. Large language models like GPT, Gemini, and Claude are prime examples. Additional training for specific purposes can be layered on top of these models to build a wide range of services. ↩
-
Intelligence Index: An evaluation index compiled by Artificial Analysis from a battery of test questions. Since the questions and formula are periodically revised, scores should only be compared within the same version and time period. ↩
-
Frontier Model: The most advanced, highest-performing AI models currently in existence. They’re developed mainly by OpenAI, Google, and Anthropic in the US, and DeepSeek and others in China. ↩
-
From scratch: In this piece, this means pre-training with randomly initialized weights rather than reusing an existing model’s trained weights. It does not mean avoiding any reference to publicly available code, architectures, or training data. ↩
-
Galapagos Syndrome: Just as species on the Galápagos Islands evolved in isolation from the mainland, this refers to a phenomenon where a country’s technology becomes optimized only for its domestic market and loses compatibility with global standards. Japan’s feature phones and Korea’s ActiveX are classic examples. ↩
-
Fine-tuning: A method of further training an already-trained AI model on data from a specific domain. The result inherits the properties of the base model, and costs and usage terms vary depending on the model and the scope of training. ↩
-
HBM (High Bandwidth Memory): Ultra-high-speed memory chips used in AI model training and inference. By stacking multiple memory chips, they achieve wide data-transfer bandwidth. Samsung Electronics, SK Hynix, and Micron are among the suppliers. ↩
-
Testbed: A stage where new technologies or services can be trial-run in a real-world environment. A market as eager to adopt AI as Korea’s makes for an excellent environment for global AI companies to validate new products. ↩
Related issues
Fable 5: Blocked Worldwide Just 3 Days After Launch
A US government directive abruptly cut off access to Fable 5 and Mythos 5, exposing the operational risks of depending on a single AI model.
SocietyRemote Work Was Already News in 1979
A 1979 BBC segment on office automation offers a way to measure what AI agents actually change inside organizations.
SocietyKorea Expands Illegal-Image Filtering to Community Uploads
From July, about 80 Korean platforms must screen public image uploads for illegal content, sparking cost and efficacy debates.
Society
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?