

Magnificent Seven Mentions Down 70%—Market Weight Unchanged
Bloomberg's coverage of the Magnificent Seven has plunged, yet the group still commands about a third of the S&P 500's value.
BusinessMentions Are Down 70%—the Weight Isn’t
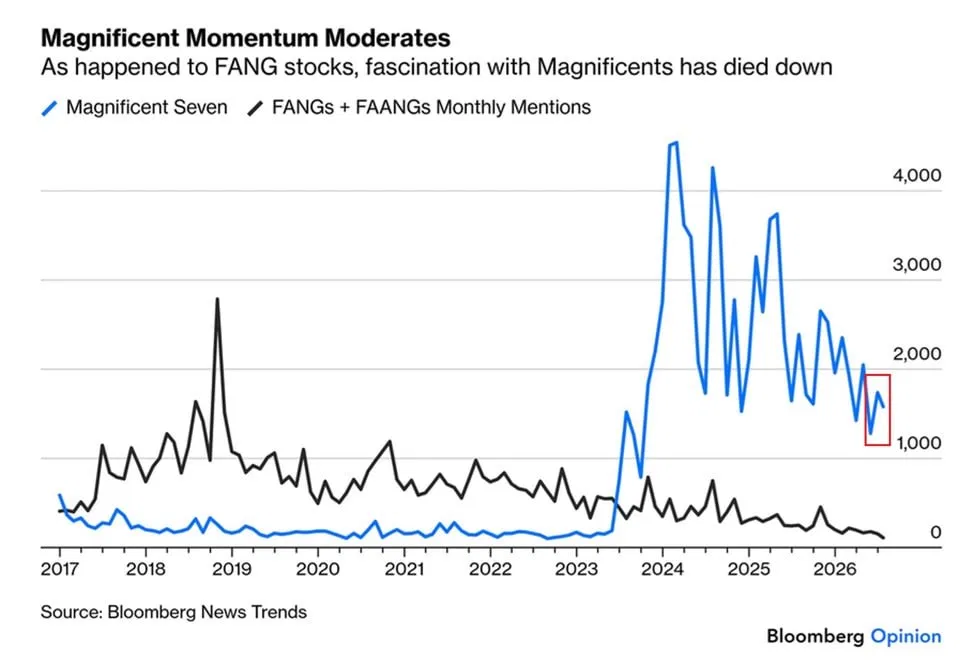
I counted how many times the phrase “Magnificent Seven (M7)” showed up in Bloomberg Terminal news articles, and the recent monthly count came to about 1,400. That’s down 70% from the peak of roughly 4,300 in Q1 2024.
But over that same stretch, these seven companies’ share of the S&P 500 hasn’t shrunk at all — it’s still sitting near a third. Only the frequency of the phrase in the headlines has dropped; the market weight itself hasn’t moved.
The reason the term gets used less isn’t fading interest — it’s that the seven companies’ stock prices no longer move in the same direction. And Wall Street is already coining the next label, one that includes companies you still can’t buy, like Anthropic and OpenAI.
Mentions of FANG and FAANG also fell 82% after their peak
This figure comes from Bloomberg News Trends1, and John Authers introduced this chart in his July 29 column.
Monthly mentions of the “Magnificent Seven” peaked at roughly 4,300 in Q1 2024 and now sit at around 1,400 — near the lowest level since Q4 2023.
Let me flag the limits of this number first. This tally only covers articles that run on the Bloomberg Terminal. So it’s not a measure of “public interest” but of the words financial journalists use. It doesn’t capture how often the term shows up on YouTube or in online communities. But for today’s discussion, that narrow scope is actually useful — it shows exactly which words the people who have to explain the market every single day are dropping.
What’s interesting is that this isn’t the first time this has happened. The previous generation’s labels, FANG and FAANG, traced the exact same curve. They peaked at roughly 2,800 mentions a month in Q4 2018, then fell to around 500 by early 2020 — an 82% decline.
Here’s a question worth checking: after mentions of FANG dropped 82%, did those five companies collapse?
No. Meta, Amazon, Apple, Netflix, and Alphabet kept leading the market afterward. Four of them carried straight over into today’s Magnificent Seven. The label falling out of use and a company’s performance faltering turned out to be two entirely separate things.
So why did the label stop being used?
Seven Companies Have to Move Together for the Label to Mean Anything
For a single label to usefully bundle several stocks, one condition has to hold: they actually have to move together. Only when they do does a sentence like “the Mag 7 rose” carry any information.
Look at 2026’s scorecard, and that condition is broken.
According to Morningstar data as of July 13, Microsoft was down 20.4% year-to-date. Over the same period, Apple was up 16.9%, and Alphabet was up 12.7%. That’s a 37-percentage-point spread within a single basket. Looking at the trailing 12 months on a Yahoo Finance basis, Alphabet more than doubled while Meta and Microsoft each fell by double digits.
 Ask “how did the Mag 7 do?” in this state, and there’s no answer. The response is opposite depending on whether you mean Alphabet or Microsoft. Bundling them under one label just hides the stock-by-stock differences.
The same holds true for the group as a whole. According to Vanguard’s analysis, while the S&P 500 rose about 9% in 2026, the Mag 7 fell 1%. MAGS, the Mag 7 ETF, has returned a cumulative 158% since its April 2023 launch — but looking at 2026 alone, it’s down 4%. A Bloomberg report from early July noted that the Mag 7 has trailed 300 stocks within the S&P 500 this year, a list that includes names like Dollar Tree and Hubbell.
Journalists using this word less isn’t about waning interest. It’s that the word can no longer explain what’s happening in the market right now. Mention volume reflects not the scale of interest but how well this word actually explains the market.
The Nifty Fifty didn’t fall together — the drops split stock by stock
This same pattern showed up half a century ago in the United States. Let’s look at the 1970s case.
From the late 1960s, a phrase circulated among American institutional investors: the Nifty Fifty2. It referred to a group of 50 large-cap growth stocks — Coca-Cola, IBM, Xerox, Polaroid, McDonald’s, Disney, and others. A powerful conviction attached itself to the name. These were dubbed “one-decision stocks” — buy once, and you’d never need to think about price again.
The valuations reflected that conviction. By the end of 1972, the group’s average price-to-earnings ratio was 41.9x — more than double the S&P 500’s roughly 19x. Polaroid alone reached 91x.
The tables turned starting in 1973. As the Bretton Woods system collapsed, inflation surged, and the oil shock hit, the broader market rolled over — but the Nifty Fifty initially held up, propped up by continued institutional buying. When they finally cracked, though, they cracked far harder than the market. While the S&P 500 fell about 48% from its peak, Polaroid dropped 91%, Disney 87%, Avon 86%, McDonald’s 72%, and Xerox 71%.
A line from a Forbes columnist writing at the time is still quoted today to describe this period: the Nifty Fifty were led out and shot one by one. I think the phrase “one by one” is the crucial part. The group didn’t collapse together at a uniform magnitude — the declines ranged from 71% to 91% depending on the stock. The label lost its explanatory power first; only afterward did each company’s individual circumstances surface.
I’ll also bring in the counterargument. In a 1998 paper, Jeremy Siegel argued that investors who held the Nifty Fifty over the long run ended up with returns roughly comparable to the broader market — meaning the prices at the time weren’t as absurd as they looked. So two interpretations still coexist: “the companies were great, but the price was the problem,” and “the price was justified over the long run after all.”
Neither interpretation contradicts today’s discussion. Whichever one you accept, they share the same conclusion: the group label failed to predict the fate of any individual company. The term “Nifty Fifty” effectively fell out of use after the mid-1970s — but Coca-Cola and McDonald’s kept growing for another half-century afterward.
The draft looks accurate and complete. No corrections needed.
The attention moved to 45 AI infrastructure companies
Let’s come back to 2026. Where did the attention that the label could no longer hold actually go?
Vanguard identified 45 companies that could be called the “AI complex” — infrastructure builders, power companies, semiconductor firms. This basket has doubled in value this year. But Alphabet, Amazon, Meta, Microsoft, and Oracle aren’t among these 45.
This overlaps with what I covered last week: model usage prices are falling while GPU rental rates are rising. I summed it up then as profit shifting from the model layer to the infrastructure layer — and the same shift shows up in stock prices. The companies the label points to and the companies where the money is flowing have become two different things.
 Let me add some balance here. Reading this as “Big Tech’s era is over” would be overreaching. The Magnificent Seven still make up about 33.8% of the S&P 500, and their projected earnings growth is more than double that of the other 493 companies. Morgan Stanley, Goldman Sachs, and JPMorgan have all argued in recent weeks that this group’s underperformance has actually gone too far. It’s not that the influence of these seven companies has diminished — it’s that the assumption they move together as one block no longer holds.
Among 2026’s Candidate Labels, One Company Isn’t Even Public Yet
So Wall Street is coining new names. This kind of naming is an old habit — line up the lineage and you can see the pattern repeat.
| Label | Era | Story it bundled |
|---|---|---|
| Nifty Fifty | 1960s–70s | Blue-chip growth stocks you buy once and hold forever |
| Four Horsemen | Late 1990s | Dot-com infrastructure (Microsoft, Intel, Cisco, Dell) |
| FANG / FAANG | 2010s | Internet platforms |
| BAT | 2010s | Chinese internet (Baidu, Alibaba, Tencent) |
| GRANOLAS | 2020 | European large-caps |
| Magnificent Seven | 2023– | Big Tech and AI |
| BATMMAAN | 2024–25 | Mag 7 plus Broadcom, an extended version |
| MANGOS / FAB 10 / AI Big 10 | 2026 | The AI race after Mag 7 |
The bottom two rows had especially short shelf lives. BATMMAAN saw brief use in 2024 before it faded without really catching on. And in 2026, there isn’t just one candidate — three are competing at once.
The three lineups differ slightly.
- AI Big 10 (Bank of America): Mag 7 plus Broadcom, AMD, and Micron. This one stays entirely within the public markets.
- FAB 10: Mag 7 plus SpaceX, OpenAI, and Anthropic.
- MANGOS: Meta, Anthropic, Nvidia, Google, OpenAI, and SpaceX.
What’s new is that the latter two include companies that aren’t publicly traded. SpaceX listed on Nasdaq on June 12, making it accessible to ordinary investors for the first time. At $135 per share, it raised roughly $75 billion — the largest IPO ever — and closed its first day up 19% at $160.95. Vanda Research read the listing as a signal that investor attention is shifting from Mag 7 toward FAB 10.
That leaves OpenAI and Anthropic. Both are frequently discussed as IPO candidates, but neither can be bought yet. And yet Yahoo Finance already has pages for OPAI.PVT and ANTH.PVT — separate tickers3 reserved for private companies.
I think this ticker is the most striking detail in the whole story. A quote page was created before ordinary investors could even buy the stock. It means the label and the narrative are being built ahead of an actual purchasable product. Every label from Nifty Fifty to Mag 7 was, in effect, a “list of things you could buy” — but the 2026 list is the first to cross that line.
Korean investors’ top US stock trades are already semiconductor names
The same shift showed up in Korea too — faster, and with sharper swings.
According to the Korea Securities Depository, Korean investors’ holdings of US stocks fell from $204.1 billion in May to $166.8 billion on July 28. That’s three straight months of decline, an 18.2% drop.
But look at what was actually being bought and sold, and the picture changes. The top name by settlement value in July was SOXL, a 3x leveraged semiconductor ETF4, followed by Micron in second, SanDisk in third, and SK Hynix depositary receipts in fourth. That’s almost exactly Vanguard’s “AI complex” list. In other words, Korean retail investors are already trading semiconductor and AI-infrastructure names rather than the Magnificent 7.
The difference was in how they accessed those names. SOXL’s share price rose 4.6x, from $47.24 on January 2 to $266.71 on June 30, and ₩71 trillion (~$51.4 billion) worth changed hands in the first half of the year alone. The turnover rate tells the real story: SOXL’s first-half settlement value was 6.7x its end-June holding balance, while Tesla — the top holding by balance — was just 0.4x. One is something people hold. The other is a day-trading vehicle.
To sum up: Korean investors got the direction right — semiconductors and AI infrastructure — but approached it through a 3x leveraged product. Because 3x leveraged ETFs track daily returns, even Direxion, the fund manager behind SOXL, explicitly warns that it isn’t meant for long-term holding.
What happens when a label becomes the product
Korea’s market offers an even sharper case study in the life cycle of a name: metaverse ETFs.
When metaverse mania peaked in 2021–2022, related ETFs flooded the market — 11 of them by mid-2022. But once thematic interest cooled, net assets drained away, and under Korean regulations, a fund whose net assets fall below ₩5 billion (~$3.6 million) for more than a month becomes subject to delisting5. One by one, they were wound down through 2025, leaving just 4 survivors.
Of the 7 that disappeared, 3 weren’t actually liquidated — they survived by dropping “metaverse” from their name and swapping in a different word. Samsung Asset Management’s “KODEX China Metaverse Active” became “KODEX China AI Tech Active.”
The underlying holdings barely changed. Only the signage did. Few examples make the point more clearly: a label isn’t a description tool — it’s a sales tool. The same dynamic is playing out in the US, where MANGOS, FAB 10, and AI Big 10 compete for attention simultaneously. In Korea, that same competition just happened to take a far more visible form: ETFs literally swapping out their name tags.
For the record, this piece is an analysis of industry structure and market narrative, not a basis for investment decisions about any specific stock or product. If you want to check the underlying numbers, please consult the primary sources linked below.
Oswarld's Lens
I’ve had to deal with category naming a lot while working on GTM strategy, and I kept noticing the same pattern. The moment a category gets a name is the moment that category is most homogeneous. A name only emerges when several things look like one thing. And from the moment the name sticks, the companies inside it start heading in different directions. The name stays fixed while the reality underneath keeps moving, so the longer the name survives, the less it actually describes.
So I treat bundled names as tools that erase differences between the components. They’re convenient when the companies inside move similarly, but once the gap widens, they hide important information. Right now, returns within the Magnificent Seven span a 37 percentage point range from top to bottom — which means hearing the name alone tells you nothing about what actually happened inside it.
When I teach data, I often ask my students a question that lands in the same place: “Who made this bundle, and by what criteria?” “Magnificent Seven” was a phrase Michael Hartnett of Bank of America wrote in a research note in 2023, and Jim Cramer spread it on air. It was never a statistical classification — it was a naming convenience. But once an ETF gets built and an index gets created around it, the naming becomes the unit of asset allocation. A name coined for convenience ends up as the actual basis on which money gets allocated.
Which is why you also have to look at the incentives of whoever is doing the naming. For sell-side analysts and asset managers, a new label is essentially a new product. Korea’s domestic metaverse ETFs surviving simply by relabeling themselves is a clean example of that incentive at work. The fact that three candidate names are circulating simultaneously right now signals that the market is unsettled — but it also signals that the name itself is being sold as a product.
As a practitioner, the standard I use is simple: whenever I see a bundled name, the first thing I check is the dispersion inside it. If the dispersion has widened, the name has already stopped being an explanatory tool and become a marketing tool. And this isn’t just about stocks. It applies just as much to projects that run internally under a single label. If eight tasks with completely different characters get grouped under the name “AI adoption,” then at some point a report written under that name stops describing reality. There comes a moment when a number like “70% progress” stops meaning anything at all.
What’s needed at that point isn’t a better name — it’s the decision to split the name apart. That’s exactly what Wall Street is doing right now. The one difference, if it counts as one, is that Wall Street is selling a new name at the very same moment it’s splitting the old one apart.
Closing
Let me sum this up in four points.
First, mentions of the Magnificent Seven have dropped 70% from their peak, but their share of the S&P 500 is still close to a third. Interest hasn’t cooled — the name has simply lost its explanatory power.
Second, FANG went through the same 82% decline, and the Nifty Fifty took the same path half a century earlier. The label stops being used as a set, but the companies inside it each perform differently.
Third, whatever label comes next already contains a company you can’t buy yet. The fact that private-company ticker pages appeared first is the evidence.
Fourth, in Korea this same life cycle has already played out as ETF name-swapping. Where “metaverse” once sat, “AI” now sits.
If you try just one thing this week, pick a bundled name that keeps coming up in Reader‘s reports or meetings. Then check with actual numbers whether the items inside it are really moving in the same direction. If the directions have diverged, that name has already stopped explaining anything.
💬 Have you seen a bundled name at work outlast the reality it once described? Tell us what the word was, and when you first felt it stopped fitting.
💬 Tell us in the comments about a bundled name that outlived its substance — we’ll feature it in the next issue. 📨 If you have a colleague in investing or strategy, please pass this issue along.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- John Authers, “The Magnificent Seven Are Riding Into the Sunset”, Bloomberg Opinion, 2026.7.29. Link ··· This is where today’s piece started. The original chart of news-mention volume is here.
- Jared Blikre, “From FAANG to MANGOS: Wall Street is searching for the next Magnificent 7”, Yahoo Finance, 2026.6.20. Link ··· This is the source data for the naming-lineage table in the body, including the story behind each label.
- “This week’s earnings scrambled everything we knew about investing in the ‘Magnificent Seven’”, CNBC, 2026.7.31. Link ··· This article introduces Vanguard’s analysis of the 45-company “AI complex.”
- “4 Charts on the Not-so-Magnificent Seven”, Morningstar, 2026.7. Link ··· This is the source for the return-dispersion data by stock. Just four charts make the divergence tangible.
- Financial News, “Seohak-gaemi (Korean retail investors trading overseas stocks) close their wallets too — overseas market trading volume hits a yearly low”, 2026.7.30. Link ··· This has the custody-balance trend and the top-settled stocks in July.
- KB, “Leveraged big spenders, the seohak-gaemi: bought and sold ₩71 trillion (~$51.4B) of 3x semiconductor ETFs in the first half of the year”, 2026.7.6. Link ··· This is the source for the 6.7x-vs-0.4x turnover comparison — a good example of separating holding from trading.
- Sisa Journal-e, “Metaverse ETFs exit one after another, unnoticed”, 2025.7.17. Link ··· This covers how the field shrank from 11 to 4, and the detail that 3 of the 7 that vanished actually survived by renaming.
Background
- Gary Smith, “The Nifty-Fifty Re-Revisited”, Pomona College. Link ··· This single piece covers the Nifty Fifty’s valuations, its decline, and even Siegel’s counterargument — it’s the backbone of today’s history section.
- “S&P 500’s Weight In Mag 7 Stocks Passes 30%”, Forbes, 2026.6. Link ··· This is the background for the concentration figures, including the counterargument that “concentration still holds up.”
- SpaceX, “Announces Pricing of Initial Public Offering”, 2026.6.11. Link ··· This is the original IPO pricing document, confirming the per-share price and number of shares issued.

📝 Glossary
Footnotes
-
Bloomberg News Trends: A feature on the Bloomberg Terminal that counts how many times a given word appears across news articles. It measures what the market is talking about — not stock prices or earnings. ↩
-
Nifty Fifty: The informal name for roughly 50 large-cap growth stocks favored by U.S. institutional investors from the late 1960s through the early 1970s. It wasn’t an official index but a customary list, so its constituents vary slightly by source. ↩
-
Private-company tickers: Identification codes assigned to companies that aren’t publicly listed. Yahoo Finance appends
.PVTto show pricing from private transactions — it doesn’t mean ordinary investors can buy at that price. ↩ -
3x leveraged ETFs: Products designed to track three times the daily return of an underlying index. Held over the long term, repeated swings up and down can cause a significant divergence from three times the index’s actual return. ↩
-
Delisting requirements for small ETFs: In Korea, an ETF becomes subject to termination and delisting if, more than one year after inception, its net asset value stays below ₩5 billion (~$3.6M) for over a month. Unlike a stock delisting, however, investors are returned the net asset value minus fees. ↩
Related issues
My Book's AI Training Royalty: $300–656 Per Copy
When my book sold for AI training at $300–656 a copy, I realized the real shift is in how content gets priced, not what it's worth.
BusinessThe 90-Day Exit Clause in Google's SpaceX Compute Deal
SpaceX posted 92% revenue growth, but its AI compute lease with Google can be canceled with just 90 days' notice after 2026.
BusinessWhy Midjourney Bought an Astrology App
Reading Midjourney's Co–Star acquisition as a bet on user experience design, not astrology
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?