

The 90-Day Exit Clause in Google's SpaceX Compute Deal
SpaceX posted 92% revenue growth, but its AI compute lease with Google can be canceled with just 90 days' notice after 2026.
BusinessA Flawless Report Card, and Five Straight Weeks of Falling Stock
On August 4th, SpaceX released its first earnings report since going public.
Q2 revenue came in at $7.81 billion, up 92% year-over-year. The loss per share was $0.09, far better than the projected loss of $0.26, and adjusted EBITDA1 hit $3.54 billion. The CFO went on record promising “a $100 billion annualized run rate by December.” On paper, there wasn’t a single line item to complain about.
And the stock started falling that very day. It dropped 13.6% on August 5th alone, closing at $108.27. That’s five consecutive weeks of decline, 20% below the June IPO price of $135, and roughly half of its peak of $225.64.
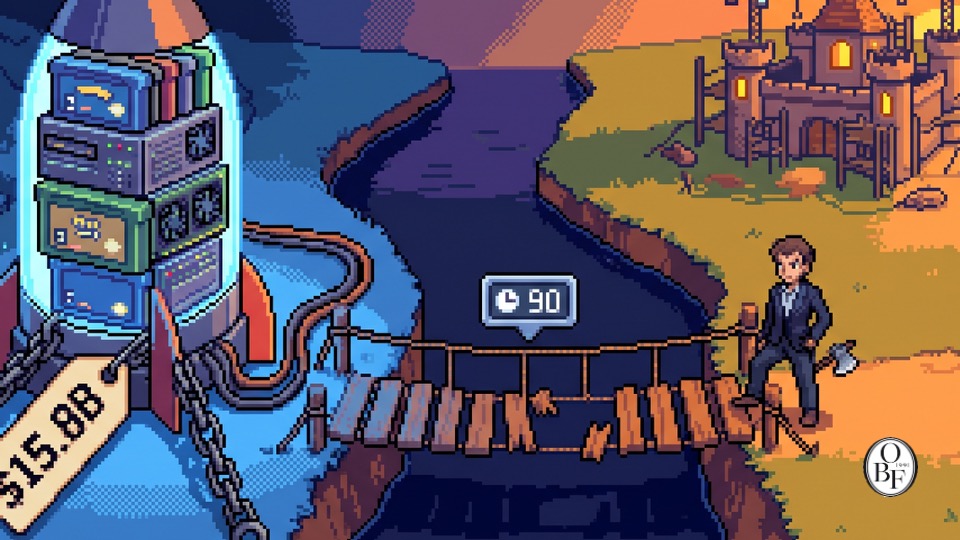
Normally, a scene like this gets filed under “lockup expiration selling” and left at that — and it’s not wrong, exactly, since today, August 6th, happens to be the day 911.5 million shares unlock. But I think there’s a stickier problem underneath. What the market read this time wasn’t the earnings report — it was the contract. SpaceX’s growth engine, its AI compute leasing business, comes with a clause letting customers walk away with just 90 days’ notice.
The Rocket Company’s Revenue No Longer Comes From Rockets
Let me first lay out what kind of company this actually is now. Last February, when SpaceX absorbed xAI in a merger (combined enterprise value: $1.25 trillion), the rocket company we knew fused with Grok and X into a single entity. So the segment breakdown on the earnings report now looks like this.
| Segment | Q2 Revenue | YoY | Operating Income |
|---|---|---|---|
| Space (Launch) | $962 million | +29% | -$542 million |
| Connectivity (Starlink) | $4.29 billion | +66% | +$1.66 billion |
| AI (Grok, X ads, compute leasing) | $2.56 billion | +247% | -$1.26 billion |
Rockets make up 12% of this company’s revenue. Only Starlink is actually profitable, and the AI segment is where growth is exploding. Both the reason the market priced this company above $1 trillion and the reason it’s marking that price down today live in the AI row of this table.
Let me dig a little deeper into the AI segment’s numbers. Adjusted EBITDA came in at a positive $1.146 billion — a swing back into the black after posting a $609 million loss just one quarter earlier, in Q1. And yet operating income for the same segment sits at -$1.257 billion. The roughly $2.4 billion gap between these two figures is mostly depreciation2.
Read together, the two numbers tell a specific story: the business is generating cash, but the depreciation on the equipment it bought to generate that cash is being booked at an even larger amount.
Spending $6 to earn $1 in revenue
That depreciation spike traces back to capex3.
SpaceX’s Q2 capital expenditure came to $18.37 billion. Of that, $15.8 billion went to AI infrastructure. Since Q1 AI capex was $7.7 billion, that’s a doubling in a single quarter. Put another way, the company poured $170 million a day — roughly ₩240 billion a day in our terms — into GPUs and data centers.
AI-segment revenue for the same quarter was $2.56 billion. So for every $1 of revenue, the company spent $6.2. Musk has said he wants to push power-and-cooling capacity to 15 gigawatts by the end of 2027, with a stretch target of 20 gigawatts. The company hasn’t issued separate 2027 capex guidance, but Piper Sandler estimates it at around $65 billion — $17 billion above prior market expectations.
For investors to accept these numbers, there’s really only one thing they need to believe: that this infrastructure will keep generating money steadily for years to come. That’s exactly how management frames it — they argue AI compute investment has a payback period4 of under a year, which makes it closer to cost of revenue than to capital expenditure.
Which is why the real question is how long these contracts actually hold up.
Google called it temporary computing capacity
SpaceX signed $14.1 billion in new cloud contracts in Q2. Two customers matter here.
Anthropic pays $1.25 billion per month through May 2029 for exclusive use of the entire Colossus 1 data center in Memphis. Google pays $920 million per month from October 2026 through June 2029 for roughly 110,000 Nvidia GPUs — that’s ₩1.27 trillion (~$927 million) a month in our currency. Combined, these two contracts alone lock in $26 billion a year in recurring compute-rental revenue.
That’s the headline. But look at the terms of Google’s contract, and you find this clause:
After December 31, 2026, either party may terminate the contract with 90 days’ notice. If SpaceX fails to deliver the committed GPUs by September 30 (after a 1-month grace period), Google may terminate immediately.
Let’s do the math. The contract starts in October 2026. Termination notice can’t be given until after December 31. Once notice is given, it takes 90 more days to take effect. So the period that’s actually locked in runs from roughly October 2026 to March 2027 — about 6 months. In dollar terms, that’s roughly $5.5 billion.
On paper it’s a 33-month, $30.4 billion contract. What’s actually guaranteed is $5.5 billion. The remaining ~82% simply doesn’t materialize as revenue if Google gives notice.
And when Google announced this deal, it described it, in its own words, as “short-term, timely bridge capacity” secured because demand for Gemini Enterprise grew faster than expected. Bridge — meaning capacity meant to be used temporarily. Alphabet is pouring over $180 billion into its own infrastructure this year alone. Once its own data centers are ready, this leased capacity stops being necessary.
The conditions attached to cost and revenue are not the same.
Costs are non-cancellable. The $15.8 billion worth of GPUs is already bought, the data center is already built, and depreciation keeps hitting the books for years regardless of whether the contract survives.
Revenue is cancellable. If Google gives 90 days’ notice, the rental payments stop.
The “payback in under a year” that management touted only holds up if the contract keeps running as scheduled. If it ends early, that payback math falls apart.
One more thing worth flagging. The company’s stated total backlog is $47.5 billion. But even just the nominal totals of the two contracts above don’t reconcile cleanly with that figure. It’s possible the cancellable portions aren’t fully reflected in the backlog — though that’s my own inference, and I’d encourage you to check the original filing’s backlog methodology yourself. Either way, the takeaway is the same. A “$100 billion annual run rate” and a “$47.5 billion backlog” are commitments of very different strength.
It’s Not Just SpaceX’s Problem
This structure is now shared across the entire AI infrastructure industry.
The clearest comparison is Oracle. Oracle’s remaining performance obligations5 have swelled to $638 billion. That’s a staggering figure. But analysts estimate that more than half of it comes from a single customer, OpenAI (this isn’t something Oracle disclosed directly — it’s an estimate based on the roughly $300 billion contract with OpenAI). In the same fiscal year, Oracle spent about $56 billion on equipment while posting a free cash flow deficit of $23.7 billion, and it’s now planning to raise $40 billion to close that gap. Oracle even added warning language to its SEC filings stating that building out AI infrastructure could pressure profitability.
 It’s the same structure. Backlog is contracted revenue not yet recognized — meaning it isn’t cash — but the capital expenditure going out the door right now, justified by those same contracts, is very real cash.
What makes termination clauses especially dangerous in this game is that most AI compute customers are companies busy building their own infrastructure. Google, Microsoft, Meta — they’re all leasing capacity only to fill the gap until their own data centers are finished. Which means a large chunk of today’s compute-leasing demand isn’t durable demand at all — it’s demand that exists only because supply is currently tight. Once the bottleneck clears, it disappears.
Of course, there’s a counterargument. Morgan Stanley’s Adam Jonas maintains an overweight rating with a $300 price target, arguing that the current stock price essentially “prices the AI business at close to zero.” Bank of America and JPMorgan have both put out targets of $235-240. Piper Sandler, on the other hand, cut its target from $156 to $140 while maintaining a neutral rating, and some investors are calling $30 the fair value. The very fact that price targets range tenfold — from $30 to $300 — is itself a signal that no one is confident right now about how durable this company’s revenue actually is.
Oswarld’s Lens
When I’m building out a GTM strategy, I end up reviewing a lot of client pipelines. There’s one thing I look at before the contract value itself: the termination clauses and the minimum commitment period.
The total contract value sales brings in and the number finance can actually put into a forecast are almost never the same. And this gap gets widest exactly when a company is doing well. When demand surges, customers sign flexible terms just to lock in a spot, and the seller accepts those terms because the headline number matters more in the moment. Both sides are being rational — for that moment. The problem is that the seller absorbs the entire burden of that flexibility. The customer gets the right to walk away at any time, while the supplier goes out and buys irreversible equipment on the strength of that same contract.
The number I weighed most heavily in this earnings report wasn’t the 92% revenue growth or the $18.3 billion in capex. It was seeing the AI segment’s adjusted EBITDA of +$1.1 billion sitting right next to an operating loss of -$1.26 billion. That’s not simply “still unprofitable.” It means the profit and loss of this business is essentially dictated by a depreciation schedule. Depreciation keeps accruing on a fixed timetable for equipment already purchased, while revenue can shrink or stop entirely depending on contract terms.
So I see today’s lockup expiration less as the root cause of the decline and more as the trigger that pulled it forward. Even if the float ratio jumps from 4.9% to 11.8%, and climbs to roughly half by the summer of 2027, the supply of shares eventually stops flowing. But a structure where cancellable revenue is used to justify buying non-cancellable equipment doesn’t end after one round — it stays on as the way the business operates.
Of course, I don’t want to look at this from only one angle. Starlink is a genuine cash generator, with 12 million subscribers and $1.66 billion in quarterly operating profit, and roughly $100 billion in liquidity is enough to keep funding investment at this scale for several more years. My conclusion isn’t “this company is at risk.” It’s that what the stock price should be pricing in right now isn’t the growth rate — it’s the quality of the contracts.
Closing
Let me boil this down to three points.
First, SpaceX’s Q2 results themselves were excellent — 92% revenue growth, beating consensus. The problem isn’t the earnings sheet; it’s the contracts that produced that revenue.
Second, the contract with Google, SpaceX’s key customer, can be terminated with 90 days’ notice any time after the end of 2026, and Google itself described this deal as “short-term, opportunistic bridge capacity” — that is, capacity meant for temporary use. Of the nominal $30.4 billion, only about $5.5 billion — six months’ worth — is actually locked in.
Third, this asymmetry — costs that are non-cancellable, revenue that is cancellable — isn’t unique to SpaceX. It’s a structural feature of the entire AI infrastructure industry right now. Oracle’s $638 billion in remaining performance obligations faces the exact same question.
Going forward, there’s really just one thing to watch: will Google issue a termination notice after December 31, 2026? Whatever disclosure comes out after that date will be the first real test of this company’s valuation. If you look closely at the backlog calculation methodology and AI-segment depreciation figures in the Q3 results, you’ll read a lot more than the headline numbers reveal.
For the record, this piece is not investment advice, nor is it a basis for any investment decision on a specific stock. All figures cited are drawn from public reporting and company disclosures, but if you’re interested, I’d encourage you to check the original filings yourself.
Lastly, I want to ask Reader something. Have you ever had a forecast completely upended by a contract renewal or termination clause — whether in SaaS, cloud, or services? Which clause caused the problem, and how did you rewrite the contract afterward? Tell me in the comments. I’ll gather these cases and write a follow-up issue on “how to measure the quality of a contract.”
💬 If a single contract clause ever blew up your revenue forecast, tell me about it in the comments — I’ll fold it into a follow-up issue. 📨 If you have a colleague working in finance or sales pipeline, please pass this along.
The English draft matches the Korean source accurately in structure, numbers, links, and terminology. No corrections needed.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- Space Exploration Technologies Corp., “Q2 2026 Earnings Release (SEC Form 8-K)”, 2026.8.4. ··· I pulled every financial figure in today’s issue directly from this filing. Be sure to check the segment-level adjusted EBITDA and the AI capex line items.
- Benzinga, “SpaceX Q2 Highlights: Double Beat, Revenue Up 92%, Backlog Hits $47.5 Billion”, 2026.8.4. ··· This has the cleanest breakdown of segment revenue and operating income. The table in today’s issue came from here.
- TechCrunch, “Google will pay SpaceX $920M per month for compute”, 2026.6.5. ··· This is the core evidence behind today’s issue. The 90-day termination clause and Google’s “bridge capacity” comment both come from here. If you only read one link, make it this one.
- 24/7 Wall St., “SpaceX Craters 12% on Soaring AI Costs”, 2026.8.5. ··· The source for AI capex doubling from $7.7 billion in Q1 to $15.8 billion in Q2, and the $65 billion guidance for 2027.
- Investing.com, “Piper Sandler cuts SpaceX stock price target on lockup concerns”, 2026.8. ··· The original source for the price-target cut from $156 to $140, and the phrase “highly profitable but cancellable contracts.”
- GuruFocus, “SPCX Q2 2026 Earnings Call Highlights”, 2026.8.5. ··· Contains management’s own words on the “sub-one-year payback period,” the 15GW target, and the ramp-up schedule for the Google and Anthropic contracts.
Background
- TheStreet, “Oracle’s $638 billion promise comes with one big catch”, 2026. ··· A piece showing the same structural pattern at Oracle. It confirms that the gap between backlog and cash flow is an industry-wide issue, not a one-off.
- Asia Economy (Asiae), “SpaceX, its first report card since going public — stock falls despite 92% revenue surge”, 2026.8.5. ··· A quick way to grasp the whole picture in Korean.
- The Motley Fool, “SpaceX’s Lockup Expires on Aug. 6”, 2026.8.5. ··· Lays out the structure of the 911.5 million-share lockup expiration and the schedule of further releases through 2027.
Past issues worth reading alongside this one
- Issue 162: The real-asset investment behind 20% of global household wealth growth, and Korea-US AI cooperation
- Issue 189: Why Google chose a reactor design that’s never been built

📝 Glossary
Footnotes
-
Adjusted EBITDA: Earnings before interest, taxes, and depreciation, with one-time items stripped out as well. Companies that have bought a lot of equipment tend to look much better on this metric than on actual operating income, so you need to look at both side by side to see the real picture. ↩
-
Depreciation: The accounting practice of spreading the cost of a big-ticket asset over its useful life rather than expensing it all at once. If you assume a GPU lasts 6 years, one-sixth of its purchase price gets charged to the income statement every year — and that charge keeps showing up even if the revenue from it stops. ↩
-
CapEx (Capital Expenditure): Money spent on assets meant to be used over several years, like data centers, equipment, and GPUs. Because it isn’t expensed in full in the year it’s spent — it flows through depreciation instead — it doesn’t show up on the income statement. You have to look at the cash flow statement to see it. ↩
-
Payback period: The time it takes to recoup an investment through the cash it generates. A “sub-one-year” payback means the cost of a single GPU is recovered in lease payments within a year — but that assumes the lease contract actually stays in force for that long. ↩
-
RPO (Remaining Performance Obligations): Money under contract but not yet recognized as revenue because the service hasn’t been delivered yet. Commonly called “backlog.” It’s a preview of future revenue, but it isn’t cash — and if the contract has a termination clause, the preview may never play out as promised. ↩
Related issues
Why Midjourney Bought an Astrology App
Reading Midjourney's Co–Star acquisition as a bet on user experience design, not astrology
BusinessRailway Dividends Funded by New Share Capital, Not Profit
In 1848, railways booked renewal costs as capital spending to fake dividends—a trick echoed in today's AI infrastructure accounting.
BusinessA 19-Year-Old With No Resume Raises $6.2 Million
Investors increasingly check GitHub activity before diplomas—here's how the yardstick for judging talent is shifting.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?