

Meta's New 2-5% Ad Fee: Who Pays the Digital Tax?
Meta will add extra fees to ads in six countries — but that cost isn't the same as a price hike for consumers.
BusinessA separate fee is being tacked onto ad spend
On March 10, 2026, Meta notified advertisers about a new Location Fee. Starting July 1, it will apply a 2% fee in the UK, 3% in France, Italy, and Spain, and 5% in Austria and Turkey. The determining factor isn’t where the advertiser is based, but which country the ad actually appears in.
Meta explains that it’s now passing on part of the cost of things like digital services taxes — expenses it previously absorbed without billing separately. For advertisers, this means an extra charge on top of their existing ad spend. Google and Amazon have similar fees. That said, the fee rates and how they’re calculated differ from company to company.
Why Digital Services Taxes Came About
Several European countries introduced digital services taxes (DST)1 around 2019-2020. The idea was to tax companies that earn advertising or intermediary revenue from a country’s users even without a substantial physical presence there. Behind this was an ongoing debate over whether the existing corporate tax framework was adequate to capture this kind of activity.
The services covered, revenue thresholds, and tax rates all vary by country. France, for instance, sets separate thresholds for worldwide and domestic digital service revenue. While major US platforms bear the brunt of these taxes, the legal criteria don’t simply define the tax as targeting “US Big Tech.” And the commission rates platforms charge advertisers shouldn’t be confused with each country’s statutory tax rate.
Amount A under the OECD’s Pillar One2 framework is a proposal to reallocate part of large multinational corporations’ profits to the countries where their markets are located, giving those countries taxing rights over that share. The related multilateral convention includes a commitment to repeal digital services taxes and refrain from introducing new ones. But reaching an agreement and actually bringing it into force are two different stages, and this framework has yet to be implemented.
The US position is also complicating negotiations. On January 20, 2025, President Trump stated that the previous administration’s commitments under the global tax agreement have no effect within the United States unless Congress adopts the relevant provisions. That said, this doesn’t mean each country’s digital tax is confirmed to stay in place permanently. It could still change depending on negotiations and domestic legislation.
How platforms bill advertisers
Adding a surcharge doesn’t erase a platform’s legal tax obligation. It’s simply passing part of the cost the platform bears back into the price of its service.
Compare how each company explains it, and you’ll find real differences.
- Google: In November 2020, it introduced DST fees of 2% and 5% in the UK and Austria, respectively. In other countries it sometimes uses the term “regulatory operating cost,” and the rate varies by country — France’s is 2%, different from the 3% Meta has announced.
- Amazon: It has charged a Regulatory Advertising Fee on ads in certain countries. Depending on the ad product and region, not just where the ad is shown but also the advertiser’s location can factor into the calculation. This should also be distinguished from the Digital Services Fee applied to sellers’ sales and fulfillment fees.
- Meta: It has announced that starting July 1, 2026, it will apply a location-based fee in 6 countries where the ad is displayed.
Even a Korean company could see a 3% fee added to its ad spend if its Meta ad is shown to users in France. Take an example of $100 in ad spend shown in Italy: a 3% location fee adds $3, bringing the total to $103. Any applicable VAT or similar taxes need to be checked separately.
All three companies share one thing in common: they bill regional costs as a line item separate from the ad spend itself. But that doesn’t mean it’s the same scheme under different names. If you’re running a campaign split across multiple platforms, you need to check the target countries and billing basis for each one individually.
Does the cost advertisers pay get passed on to consumers?
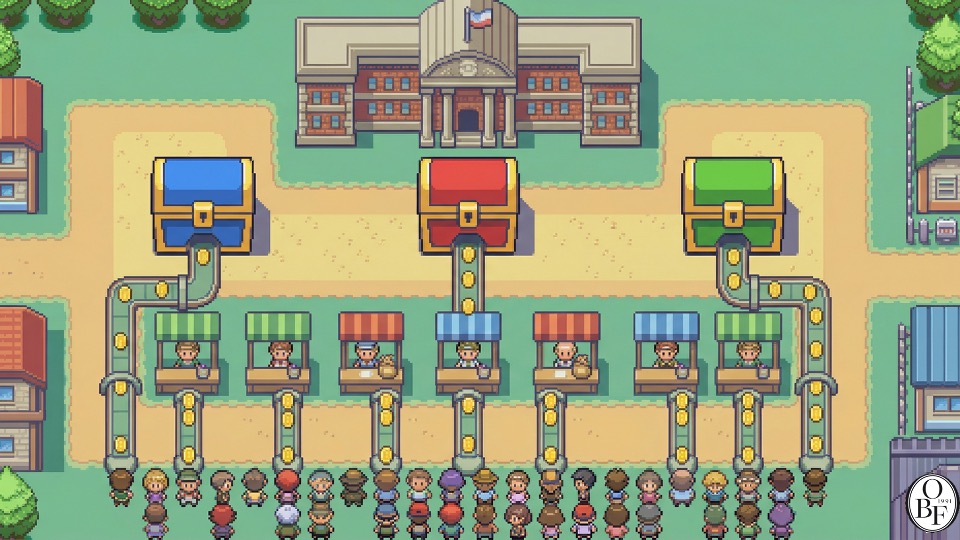
When a location fee gets added, the amount advertisers pay increases. So does that mean consumers buying the product end up paying more too?
Economics draws a distinction between who is legally responsible for paying a tax and who actually bears the economic burden. This is called tax incidence3. In this case too, how the burden gets split among platform, advertiser, and consumer depends on how the market responds.
Advertisers might absorb the added cost by accepting lower profits, or they might cut their ad spend or other expenses. They could also raise product prices—but that’s harder to do when competition is fierce or customers are price-sensitive. And if ad budgets shrink, that can end up affecting the platform’s revenue too.
So the mere fact that a fee got added doesn’t let us conclude that the entire digital tax burden falls on the final consumer. The amount billed directly to advertisers and the ultimate burden borne across the whole market are two different things.
Governments need to factor these price responses into how they design taxes, and advertisers need to calculate their actual spending and performance separately from whatever explanation the platform gives.
Trade negotiations affect taxes, too
The US government has long argued that Europe’s digital services taxes discriminate against American companies — a position squarely at odds with the countries that have adopted such taxes.
A memo from President Trump dated February 21, 2025 directed the USTR to determine whether to reopen Section 3014 trade investigations into digital taxes imposed by France, Austria, Italy, Spain, Turkey, and the UK. It’s important to distinguish between an instruction to consider reopening an investigation and an actual, confirmed retaliatory measure.
Against this backdrop, when a platform itemizes “costs arising from digital taxes” separately, advertisers become aware of the link between the tax and their rising ad spend. I think this kind of line-item disclosure carries a political message as much as it explains costs. That said, whether advertisers’ frustration is actually directed at the intended target is a separate question that needs its own verification.
Canada announced on June 29, 2025 that it would repeal its Digital Services Tax to advance trade negotiations with the US, and suspended the tax collection scheduled for the following day. Because the law was already in force at that point, this differs from a case of “withdrawal right before implementation.” The repeal bill received royal assent on March 26, 2026. This case shows that digital taxes aren’t purely a matter of domestic revenue policy — they’re also a bargaining chip in trade negotiations.
Oswarld’s Lens
From a GTM strategy perspective, what I look at first is how the cost is explained to customers, and by what number customers judge performance.
Instead of folding the cost into ad rates, if you list tax-related fees separately, advertisers can more easily attribute the price increase to external policy. Even so, this explanation alone doesn’t erase Meta’s responsibility for its pricing decisions or the burden placed on advertisers.
When calculating budgets, you need to look only at ad spend in the applicable country. If you spend ₩10,000,000 (~$7,200) on ads in a country with a 3% fee, the fee comes to ₩300,000 (~$216). There may be other taxes that apply on top of that. If you estimate Meta’s profit increase by multiplying total European revenue by an average fee rate, you miss the differences by country, timing of implementation, and shifts in ad demand.
Advertisers need to recalculate their cost per acquisition and ad-spend-to-revenue ratio, fees included. If another platform delivers better performance, they might shift budget there. Conversely, if Meta still performs well even with the fee included, they might keep their spend there. Not every advertiser will make the same choice.
If international tax negotiations get settled, that could help narrow the differences between countries’ rules. But a single negotiation won’t resolve every issue around ad costs. For anyone actually running ads, the first priority is reflecting the tax and fee changes in their real budget.
Closing
Before the July 1st rollout, there are three things I’ll be checking.
- The countries where ads actually run, and each country’s fee rate.
- Any charges added on top of the campaign’s set budget.
- Final ad performance once fees and applicable taxes are factored in.
The ad spend shown in the dashboard may not match the actual amount billed, so it’s worth making sure your budget sheet and performance reports are calculated against the same figure.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
-
Amazon Ads, Regulatory Advertising Fees. : Explains how Amazon’s ad products apply fees by country.
-
Canada Department of Finance, Canada Rescinds Digital Services Tax to Advance Broader Trade Negotiations with the United States, June 29, 2025.
-
Canada Revenue Agency, Digital Services Tax repeal notice. : Confirms royal assent of the repeal bill on March 26, 2026.
-
The White House, Memorandum on the Global Tax Deal, January 20, 2025.
-
The White House, Memorandum on Defending American Companies and Innovators from Overseas Extortion and Unfair Fines and Penalties, February 21, 2025.
-
Meta Platforms, “Location Fees for Ads”, Meta Business Help Center, 2026. : Meta’s own explanation of its location-fee policy.
-
Google Ads Help, “Jurisdiction-specific surcharges”, Google, 2020-2026. : Google’s breakdown of the DST-related surcharges it applies by country, including rates and effective dates. Note that these differ from statutory tax rates.
-
Skadden, “Trump Revives and Expands the Battle Over Digital Services Taxes”, 2025. : A legal-perspective summary of the Trump administration’s strategy on digital taxes.
-
Tax Foundation, “Global Tax Agreement: Details & Analysis”, 2025. : Explains the difference between OECD Pillar 1 and Pillar 2 — Pillar 1’s reallocation of taxing rights is a distinct regime from Pillar 2’s global minimum tax.
-
Congressional Research Service, “The OECD/G20 Pillar 1 and Digital Services Taxes: A Comparison”, 2024. : A U.S. congressional report structurally comparing digital services taxes with the OECD’s reallocation of taxing rights.
-
EY, “Taxation of digital services has come back in focus”, 2025. : An analysis from EY’s 2025 tax risk survey showing that DSTs have emerged as companies’ top concern.
-
Bruegel, “Has the global minimum tax survived Trump?”, 2026. : Examines how the global minimum tax has changed under the Trump administration — a topic distinct from this piece’s focus on Pillar 1.
Footnotes
-
A digital services tax (DST) is a tax that individual countries levy on revenue from digital services. The taxable base, revenue thresholds, and deductions or exemptions vary by country. It differs from a standard corporate income tax, which is based on profit. ↩
-
Pillar 1’s Amount A is a mechanism intended to reallocate a portion of large multinational corporations’ profits — for those meeting certain criteria — to the countries where their markets are located, giving those countries taxing rights. The related multilateral convention also addresses the elimination of digital services taxes, but this requires the convention to actually take effect and for individual countries to implement it. ↩
-
Tax incidence is the concept of who ultimately bears the economic burden of a tax. That burden can be split among parties depending on price changes, the responsiveness of supply and demand, and competitive conditions. ↩
-
Section 301 of the Trade Act: a U.S. law that allows the U.S. Trade Representative (USTR) to investigate unfair trade practices by foreign governments and impose retaliatory measures such as tariffs. It was also used as the legal basis for tariffs on China during Trump’s first term. ↩
Related issues
Musk Admits xAI Distilled OpenAI Models in Court
Under oath, Musk said Grok's training partly relied on OpenAI's models, raising questions about what standard should apply.
BusinessSteve Blank on the Startup Whose Market Moved While It Built Tech
A six-year-old portfolio bet shows how autonomy tech, customers, and competitors can all shift before a product ships.
BusinessHow Meta and Block Are Splitting Up Management Work
Both companies are cutting management layers while redistributing reporting, prioritization, and talent development to new roles.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?