

How Aging Strains Pension Funding in Europe and Korea
As populations age, the ratio of contributors to retirees is shifting fast—here's how Europe's and Korea's pension systems differ.
BusinessPay-As-You-Go: Paying Pensions With Today’s Contributions
In many European countries, public pensions work like this: the contributions paid by today’s working generation directly fund the pensions of today’s retirees. This is called the pay-as-you-go system1.
Korea’s National Pension Service, by contrast, runs a partially funded system that also manages an accumulated reserve fund. It’s not a scheme where the contributions I pay simply pile up in my own individual account, but it’s also different from a pure pay-as-you-go system that hands the entire premium straight to today’s retirees. When comparing Korea to Europe, this distinction has to come first.
When the population paying premiums grows, along with their income, it’s easier to keep a pay-as-you-go system financially sound. But when the number of contributors shrinks while the number of beneficiaries grows, governments have to adjust premiums, benefits, tax subsidies, and the like. The Economist recently criticized this burden, writing that “the welfare state looks like a pyramid scheme.” You can’t simply equate a pension system with fraud, but the phrase does point to the burden being passed on to the next generation.
🇪🇺 Europe’s Generational Divide in Housing and Pensions
The clearest place to see Europe’s generational wealth gap is housing.
Baby boomers who bought homes early got in at prices far lower than today’s. They took out mortgages at high interest rates, but even after paying those off, home prices kept climbing. Even adjusted for inflation, European housing prices rose 25% over the past decade, and rents rose faster than income. As a result, nearly a quarter of Europeans born in the 1980s are still living with their parents at age 30 — 1.5 times more than the same age group 20 years ago. This overlaps with the housing situation in Korea, which we’ll look at later.
It’s hard to say baby boomers were simply lucky, because the outcome reshaped the conditions facing the next generation. Rising home prices owed more to timing than to individual investment skill, and those higher prices came back as a straight burden on the generation that followed when it came time to buy.
Pensions are the other issue worth examining alongside housing. While generational conflict and policy debate over real estate continued, pension burdens kept growing with far less attention. This, too, is a pattern repeating in Korea.
How much public pensions, private pensions, and earned income each contribute to retirement income varies by country. In many European countries, pay-as-you-go public pensions play a large role. As population aging increases the elderly population relative to the working-age population, the fiscal burden on today’s working generation grows heavier. The EU’s 2024 Ageing Report puts aging-related costs at 24.4% of GDP, with pension spending at 12.2%. There’s also variation by country: pension spending accounts for 15.5% in Italy and 14.6% in France.
As the share of elderly voters grows, it becomes harder to cut pension and care budgets. The article cites the median age of voters in France’s most recent presidential election as 52 — a figure showing the aging of the electorate, though it doesn’t mean retirees make up a majority. A way must be found to sustain both retirement security and investment in education and R&D within limited budgets. Maxime Sbaihi, an economist at the French demographic think tank Club Landoy, put the problem of generational representation starkly:
“The future of democracy is being decided by voters who have no future.”
We also need to weigh what kind of support younger generations get in housing, childcare, and education. The French thinker Raymond Aron warned that “an aging society will be gripped by a spirit of renunciation.” I bring up this warning not to blame older generations, but to ask whether retirement security and investment in the next generation can be sustained together.
🇰🇷 Korea’s Aging Is Outpacing Europe, and the Dependency Ratio Is Spiking
Korea’s population is aging especially fast. Pensions are a subject that easily spirals into politics and generational conflict, but we need to talk about how to share the burden based on population projections and fiscal forecasts.
According to the 2025 Statistics on the Aged, Koreans aged 65 and older now make up over 20% of the population. It took the country about 18 years to go from an “aging society” (7%) to an “aged society” (14%), and then roughly another 7 to 8 years (depending on the statistical baseline) to reach a “super-aged society” (20%). That’s a much shorter runway than the United States, which took 15 years for the same transition, or Japan, which took 12.
Under the 2025 pension reform, the contribution rate will rise by 0.5 percentage points a year starting from 9.5% in 2026, reaching 13% by 2033. Compared to the previous rate of 9%, the final contribution rate is about 44% higher. The nominal income replacement rate, based on a standard 40-year enrollment period, has been adjusted to 43%. This rate applies to enrollment periods from 2026 onward — it does not mean an across-the-board increase in benefits for people already receiving pensions. Younger workers will benefit from the higher replacement rate for their future contribution years, but they’ll also be paying the higher premiums for far longer. At the time of the reform, projections pushed back the expected fund depletion date from 2056 to 2064.
Investment performance also affects the fund’s finances. The National Pension Service announced in February 2026 a provisional 2025 return of 18.82%, with year-end reserves of about ₩1,458 trillion (~$1.05 trillion). Domestic equity returns came in at 82.44%. Following the strong results, some projected that fund depletion could be pushed back even further — but a single year’s performance and the rate-of-return assumptions meant to hold for decades are two very different things.
The 2025 Statistics on the Aged also project the old-age dependency ratio to rise from 29.3 in 2025 to 77.3 in 2050 and 118.5 in 2072 — that is, the number of people aged 65 and older per 100 people aged 15 to 64. This is not the ratio of actual workers to pension recipients. The real burden will vary depending on how much older people participate in the economy and how productive they are, but the underlying shift in population structure is unmistakably large.
Housing conditions echo Europe’s, too. For Korean households that own their homes, home prices average 6.3 times annual income nationwide, and 8.7 times in the greater Seoul area. It now takes 7.9 years on average from becoming a household head to buying a first home — the longest wait since 2019. When home prices rise faster than income, the gap widens between the generation that already owns property and the one that doesn’t yet.
Korea also has to reckon with elderly poverty. The relative poverty rate among people aged 66 and older is 39.7%, the highest in the OECD. Easing the contribution burden on younger workers and guaranteeing a basic standard of living for older people are problems that have to be solved together. Lumping an entire generation together as “rich” or “poor” obscures the inequality that exists within each one.
Fiscal Adjustments When the Number of Contributors Falls
A shrinking pool of contributors doesn’t mean pension payments stop overnight. What it does mean is that keeping current premium rates and benefit terms unchanged becomes harder to sustain.
A pension is a statutory social insurance program, and the state can adjust premiums, benefits, eligibility age, and fiscal support. This is fundamentally different from a fraud scheme that pays promised returns using only new members’ money. The real question is how to allocate the rising costs of an aging population, and among whom.
It’s also hard to pin the decline in birth rates on the choices of a single generation. Housing costs, employment conditions, and caregiving support all play a role. Oversimplifying the cause and blaming one generation only makes it harder to reach consensus on the institutional adjustments that are actually needed.
How a pension system is funded also affects how much long-term investment capital accumulates in the economy.
Funded private pensions like America’s 401(k)2 pool contributions and invest them. A portion of the accumulated pension assets can flow into corporate and venture investment. CEPS explains that changes to pension fund investment rules in the U.S. contributed to the growth of venture capital there. Europe has funded pension schemes too, but because systems and investment rules vary by country, it’s difficult to reduce this to a single comparable figure.
CEPS suggests that fixing Europe’s shortage of growth capital for companies requires examining the investment rules governing pension and insurance assets as well. The supply of long-term capital can influence industrial growth, but the tech gap between Europe and the U.S. can’t be explained by pensions alone. Market fragmentation, regulation, and investment in talent and R&D all need to be considered together.
Immigration is one way to grow the working-age population, but it requires social consensus and support for integration. Greater labor force participation by older adults and women, along with productivity gains, can also ease the fiscal burden. Improving conditions for childbirth takes a long time to show results, so it needs to be pursued alongside other measures.
The point at which a fund runs dry isn’t a fixed date — it’s a projection calculated from assumptions about population, wages, returns, and policy. You can’t say “no matter how good returns are, it will definitely hit zero in 2071.” As reserves shrink, the burden that must be covered through premiums and taxes grows, but depletion doesn’t automatically mean pension payments stop. That’s precisely why long-term fiscal solutions need to be worked out while the fund still has money left.
Oswarld’s Lens
I see this as a question of how you adjust a system when population and economic conditions change. That’s exactly why we need to reopen the debate on the National Pension Service’s long-term finances.
There’s a pattern I’ve noticed again and again while building GTM strategies. While a market is still growing, weaknesses in pricing or revenue structure stay hidden. Once growth stalls, it becomes hard to sustain profits under the old terms. Pensions serve a different purpose than companies do, but they’re similar in this sense: when the conditions surrounding a system change, you have to re-examine the original design. In a shrinking population, we need to talk about how to keep the retirement guarantees we’ve promised.
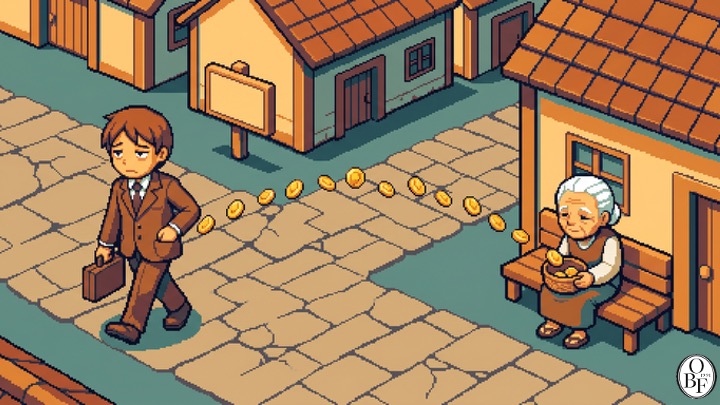
With the KOSPI and KOSDAQ recently surging, there’s a mood forming that says “the National Pension Service’s returns are so good right now, what’s the problem?” Strong returns do help the fund’s finances, but a single good year doesn’t mean the long-term fiscal problem is solved. The National Pension Service posted -8.22% in 2022 and -0.92% in 2018. The National Assembly Budget Office has flagged exactly this point: “a steady 4.6% every year is not the same as an average of 4.6% that includes negative years.” One good year in the stock market doesn’t change the country’s demographic structure.
In Korea, when adjusting the premium burden, we also have to keep elderly poverty in view. The 39.7% relative poverty rate among those 66 and older that we looked at earlier is exactly why cutting benefits alone can’t fix the finances.
I don’t think the premium rate should be the only thing on the table. We also need to examine, together, how to maintain the current partial-funding structure, how to design retirement and benefit-eligibility ages, and at what risk level pension assets should be managed. If fiscal support is needed, the tax burden that comes with it needs to be explained too. The National Pension Service is a social safety net, so this can’t be reduced to a matter of individuals saving for their own retirement.
Closing
Both Europe and Korea face growing pension-finance burdens as their populations age. But Korea’s conditions differ in two key ways: it has an accumulated reserve fund, and old-age poverty is severe. Alongside efforts to raise investment returns, we need a concrete discussion of how to divide the burden among contributions, benefits, and fiscal support.
What the National Pension needs isn’t a depletion date that fuels anxiety, but an explanation of how the finances would change under different assumptions, and what adjustments are being prepared.
How do you see the National Pension, dear reader? Do you believe you’ll get back what you put in? Have you already started other retirement preparations? Let me know in the comments.
Looking through the fragment, everything matches well. Let me verify counts and check for any Hangul remnants or issues.
The draft looks accurate and complete — all links, numbers, headings, and footnotes match the source. No Hangul remains.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
-
National Pension Service, 2025 Fund Management Provisional Results, 2026.2.27. : Shows the annual return and the fund’s year-end size.
-
National Pension Service, Pension Reform Guide : Explains the contribution-rate hike schedule and the scope of the income-replacement ratio.
-
The Economist, “How the boomers screwed Europe”, 2026. : The article that sparked today’s newsletter. It analyzes Europe’s generational inequality along three axes — housing, pensions, and political structure.
-
National Pension Service, “National Pension Mid-Term Fiscal Outlook (2025-2029)”, 2025. : Shows, scenario by scenario, how the fund-depletion date shifts after adjustments to the contribution rate and income-replacement ratio.
-
Financial News, “Amid Stock Market Tailwinds, National Pension’s Projected Depletion Pushed Back 4-7 Years”, 2026.6.21. : A recent, balanced piece covering the National Pension’s strong returns, the delayed depletion timeline, and the limits of that outlook.
-
CEPS, “It’s finally time to leverage pension funds to foster EU productivity”, 2025. : A contribution discussing Europe’s rules on pension and insurance asset investment and financing growth capital for companies.
Background
- European Commission, 2024 Ageing Report, 2024. : The official report projecting the aging-related costs of the EU’s 27 member states through 2070. Shows the trajectory of pension, healthcare, and care costs as a share of GDP.
- Presidential Committee on Aging Society and Population Policy, “2025 Statistics on the Elderly”, 2025. : Contains the base data on Korea’s entry into a super-aged society and its projected dependency ratio.
- Speedinvest, “Build in Europe: How Europe Can Fix Its Growth Capital Gap”, 2026. : A recent report quantitatively comparing the venture-capital investment gap between European and American pension funds.
- OECD, Pensions at a Glance 2025, 2025. : Allows a side-by-side comparison of pension spending outlooks and shifting dependency ratios across OECD member countries.
Footnotes
-
Pay-As-You-Go (PAYG): A system in which the contributions paid by today’s working generation fund the pensions of today’s retired generation. Under a funded system, contributions are accumulated in a fund and invested, with the accumulated capital and investment returns used as the source of benefit payments. This does not necessarily mean the funds are managed through individual accounts. ↩
-
Funded Private Pension: A system in which contributions an individual pays during their working years are accumulated and invested in a separate account, and at retirement the individual receives a pension drawn from that accumulated fund. The U.S. 401(k) is a representative example. ↩
Related issues
Gemini 3.6 Flash: Why Cost-Per-Task Beats Price-Per-Token
The real competition now is which model finishes the same job using fewer tokens, not which one charges less per token.
BusinessAI Took the Grunt Work—So Juniors Lost Their Classroom
As AI absorbs entry-level tasks, the informal apprenticeship that once trained juniors is quietly disappearing.
BusinessNewspaper Stocks Fell Years Before Profits Did
A 2002-2007 newspaper stock chart shows how investors can price in a decline long before earnings confirm it.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?