

Virtual Cards Built Just for AI Agents
How much spending power should an AI agent get? Prepaid limits, approvals, and dispute handling are the open questions.
SocietyCards Made Specifically for AI Agents Are Here
AgentCard is a service that issues virtual cards for AI agents to use when making payments. The pitch is simple: set a spending cap for each task, and let the agent handle payment within that boundary.
For instance, an agent tasked with buying reference materials might get a $5 limit, while one purchasing software gets $50. Rather than granting broad access to your main credit card, you can restrict spending to match exactly what each task requires.
Honestly, I get the sense that the solution arrived before the problem was fully defined. What seems more urgent is figuring out which purchases can safely be delegated to an agent in the first place. Still, payment companies are clearly gearing up for this demand. Looking at how AgentCard operates alongside the plans from Visa, Mastercard, and Stripe reveals what still needs to be worked out.
Giving Agents ‘Payment Authority’
AgentCard introduced ways for developers to attach payment functionality to agents, either through the CLI1 command-line tool or MCP2 integration. Using a prepaid virtual card, you can set the top-up amount in advance. But having a Visa card doesn’t mean it’ll work at every online store. Payments can still be declined depending on whether a merchant accepts prepaid cards, country restrictions, or additional authentication requirements.
Per-card limits cap how much an agent can spend at once. But not every problem from a bad purchase stays within the card’s balance. Unwanted contracts or recurring subscriptions can still arise, and personal information may get passed along during the order process. Canceling a payment and getting a refund is a separate matter you still have to deal with.
Corporate expense management works the same way — cards get split by employee or team, each with its own spending limit. Applying similar controls to agents is essentially the same idea. Handing out separate cards also makes it easier to trace which task generated which cost.
If it were me, I’d start by assigning agents small tasks where the item and the store are already fixed. For larger purchases or anything that turns into a recurring payment, I’d have a human give final approval. What matters is watching both how well the agent places orders and whether a human can catch and cancel a bad order when one happens.
How Payment Companies Are Building Authentication and Authorization
Beyond spending limits, payment companies are working through the agent’s identity, the scope of purchases users have authorized, and how payment information gets transmitted. That’s because when a merchant receives a purchase request, it needs to be able to verify whose authority the order was placed under.
Visa announced Visa Intelligent Commerce in 2025 and has been building out infrastructure for agentic payments since. In October of that year, it unveiled the Trusted Agent Protocol, a specification that helps merchants verify requests from trusted agents. According to Visa’s December announcement, more than 100 partners have joined, and a limited pilot has processed several hundred real transactions. Visa has also projected millions of users by the end of 2026 — though that figure is Visa’s own forecast.
Mastercard’s Agent Pay, announced in April 2025, handles both agent registration/verification and payment tokens together. Here, a token is data used in place of a card number to complete a transaction. Verifying an agent’s identity and securely transmitting payment information are two separate needs that each require their own mechanism. Mastercard announced a collaboration with Microsoft and others, saying it would let consumers control their spending and use dispute-resolution processes if something goes wrong.
Stripe and OpenAI jointly announced the Agentic Commerce Protocol (ACP) in September 2025 — an open standard defining how an agent transmits order and payment information to a merchant. ChatGPT’s Instant Checkout, launched alongside it, initially supported products from US Etsy sellers, with expansion to Shopify sellers presented as a planned next step at launch.
Users review the purchase details and authorize payment. Payment information travels via a scope-limited token3, and the merchant decides whether to accept the order. Shipping, returns, and customer service all remain the merchant’s responsibility. ACP is designed to plug into existing commerce systems and payment processors.
Payment Technologies That Solve Different Problems
These services and standards sometimes substitute for one another, but they can also work together. The distinctions become clearer once you sort them by which problem each one solves.
The first is spending limits. Prepaid cards or single-use virtual cards set a cap on how much can be spent. They can run on existing card payment networks, but security obligations4 and integration methods differ depending on who holds and processes the card data.
The second is purchase authorization and order verification. Visa and Mastercard’s agent authentication, ACP’s order-and-payment integration, and Google AP2’s delegated-purchase records all address this problem. AP2 is designed to leave a signed record of what the user authorized and which product and price were confirmed. Since it’s a protocol that supports multiple payment methods, not just cards, it would be a mistake to understand it merely as a technology for bypassing card payment networks.
The third is small-value payments for online services. Coinbase’s x402 returns an HTTP 402 “payment required” response to a web request, then delivers the data once payment is made. At launch, it introduced per-API-call payments using stablecoins like USDC. This approach can be used not just by agents but by ordinary software as well. I covered related discussion in an earlier piece on agent payments and Korea’s response.
Bringing these technologies into real-world operations requires the ability to handle errors based on purchase records — because the issue changes depending on whether an order fell outside what the user authorized, or whether the merchant shipped the wrong item. Existing card dispute and return procedures may still apply here. Beyond that, you’ll need to check the terms of service and operating procedures to see how the roles of agent operators and payment companies connect.
Oswarld’s Lens
Watching this trend unfold, I’m reminded of the early 2000s, when online payments were just getting started.
Getting people comfortable with typing card details into a website to buy something took more than just a checkout screen — it required parallel progress on protecting payment data, protecting buyers, and building processes to dispute botched transactions. I think the same holds true for agent payments. A successful demo of a completed purchase doesn’t tell you whether this is something you’d trust to run day in and day out.
Services like AgentCard offer a way to experiment using the existing card infrastructure. Once new protocols become widespread, their role may shift, but I don’t think that makes virtual cards and spending limits obsolete. Even with a standard for authenticating agents, someone still has to decide how much they’re allowed to spend.
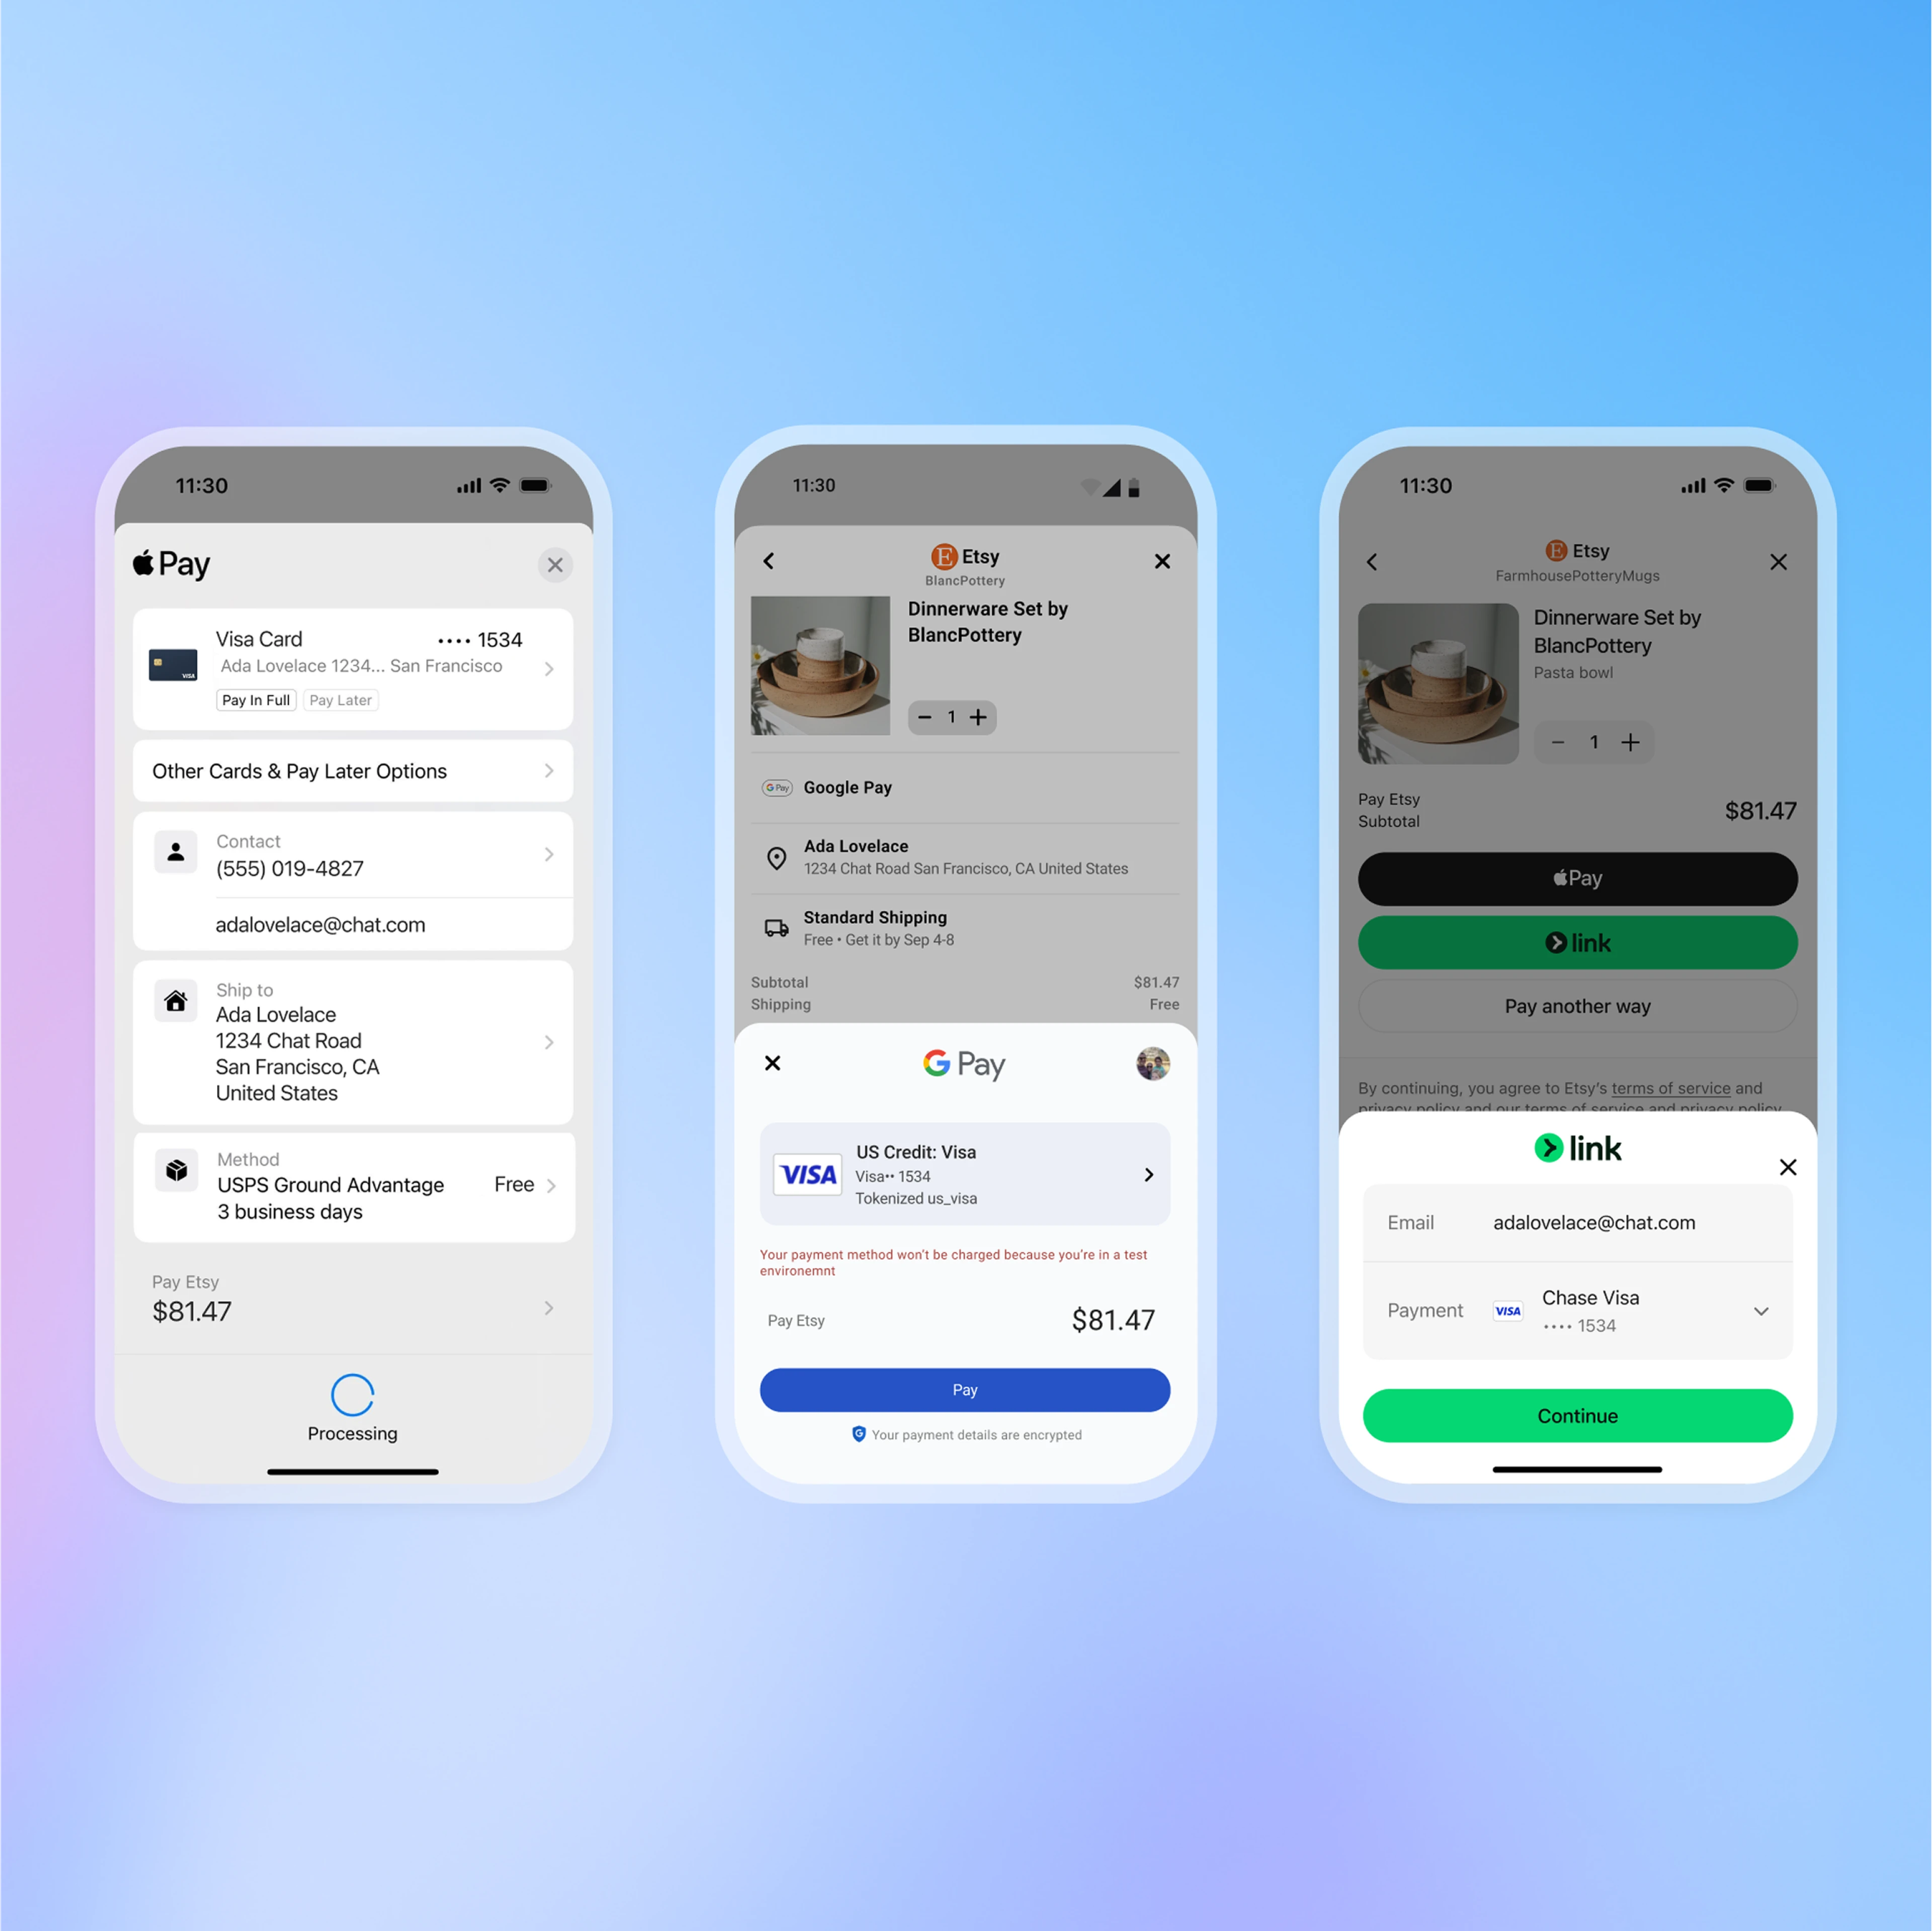
An example screen showing how a purchase is reviewed and paid for inside ChatGPT.
What interests me more is the situation in Korea. Whether a Korean merchant can sign up directly for Stripe’s payment services is a separate question from whether a card issued in Korea can be used to pay at an overseas store. You can’t judge whether ACP is viable simply by checking whether Stripe is available to businesses in a given country. What matters is how domestic payment gateways (PGs) and merchants actually connect to it.
NHN KCP took part in Google’s AP2 announcement. What matters is whether this kind of collaboration translates into real order, payment, and cancellation functionality for domestic merchants. Even when watching demos unveiled overseas, it’s worth checking whether they also support Korea’s domestic authentication methods and customer-service procedures.
When I judge whether to adopt something like this, there are three things I check first: whether the scope of purchases entrusted to the agent gets logged, whether it stops when a limit is exceeded or conditions change, and whether a human can cancel a botched transaction. Only once these pieces are in place will people who hand over payment authority actually feel safe using it.
Closing
If you want an agent to handle the purchase itself, you need to define its payment authority precisely. A prepaid card is one way to cap spending, while authentication, ordering, and payment standards are the means by which that authority gets communicated to merchants and payment processors. Only when the two work together properly can a human-approved purchase actually execute correctly.
If you’re reviewing this for practical work, it’s worth reading through the transaction process in the ACP documentation linked below. It explains exactly what information the buyer, the agent, the merchant, and the payment processor each exchange with one another. It should help you identify the steps in your own service where human confirmation is needed.
Looking at this fragment against the Korean source, everything matches well: all links, image, footnotes, numbers, and glossary terms (Oswarld, Kwangseob Ahn) are correctly rendered with no Hangul remaining.
The draft is already correct. Here is the output:
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
- AgentCard: A virtual card service for agents. Features and terms of use may change.
- Stripe, Developing an open standard for agentic commerce, 2025.09.29: Explains ACP’s purpose and the roles of each participant in a transaction.
- OpenAI, Buy it in ChatGPT, 2025.09.29: The initial scope of Instant Checkout and the purchase-approval process.
- Visa, Visa and Partners Complete Secure AI Transactions, 2025.12: An announcement covering pilot transaction results and next steps.
- Mastercard, Mastercard unveils Agent Pay, 2025.04.29: An announcement on agent verification and payment tokens.
- Google Cloud, Announcing the Agent Payments Protocol (AP2), 2025.09.16: Documents purchase-delegation records and participating companies.
- Coinbase, Introducing x402, 2025.05.06: Explains how HTTP requests are linked to payments.
- Stripe, Global availability: The scope of service support depending on a business’s location.
Footnotes
-
CLI (Command Line Interface): A way of operating a program using text commands. ↩
-
MCP (Model Context Protocol): A communication standard for connecting AI programs to external tools or data. ↩
-
Payment token: A value used in place of directly transmitting payment information such as a card number. Depending on the service design, it can restrict which merchants, amounts, or number of uses are allowed. ↩
-
PCI DSS: A security standard for protecting payment card information. The scope and obligations vary depending on how card data is stored, processed, or transmitted. ↩
Related issues
Why Chinese Firms Are Racing to Install OpenClaw
From install lines to messenger hookups, here's what my Chinese clients are telling me about OpenClaw's sudden rise.
SocietyHow Yakult Delivery Workers Check on Their Neighbors
Japan's Yakult Ladies and Korea's hy delivery workers quietly track elderly customers' well-being during routine drop-offs.
SocietyClaude's Military Use: Do Principles Hold in Contracts?
I trace Anthropic's clash with Washington through statements and contracts, separating military AI use from human control.
Society
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?