

Scaling AI Needs Power Grids, Copper, and Refineries
Software may be easy to build with AI, but running it at scale still depends on electricity, copper, and refining capacity.
BusinessBuilding AI vs. Running AI
In 2011, Marc Andreessen wrote a piece for The Wall Street Journal titled “Software Is Eating the World.” His argument was that software companies would upend how business gets done across industries from film to retail. He pointed to development tools and the cloud as evidence, noting how much cheaper it had become to launch a service.
A recent column in The Economist by Paul Achleitner, former chairman of Deutsche Bank’s supervisory board, takes a different angle—focusing on physical resources. His argument: the easier AI makes it to build software, the more energy, minerals, and manufacturing capacity matter. That perspective sent me digging through materials on electricity, copper, and refining.
Even If Code Ships Faster, Work Remains
A software business needs development capability and deployment infrastructure. On top of that, it needs the ability to understand customers and run services reliably. Code volume alone can’t explain competitiveness.
AI helps with some tasks—drafting and revising code. “Vibe coding,” where you describe the functionality you want in natural language, is an expression that emerged from this shift. But defining requirements, verifying errors and security, and connecting to existing systems still require people and money.
Running an AI service comes with its own constraints. You need space for servers, power, and materials for equipment. Even as software gets built faster, the timeline for securing these resources doesn’t shrink along with it.
Energy: Data Center Power Demand Projected at 945TWh by 2030
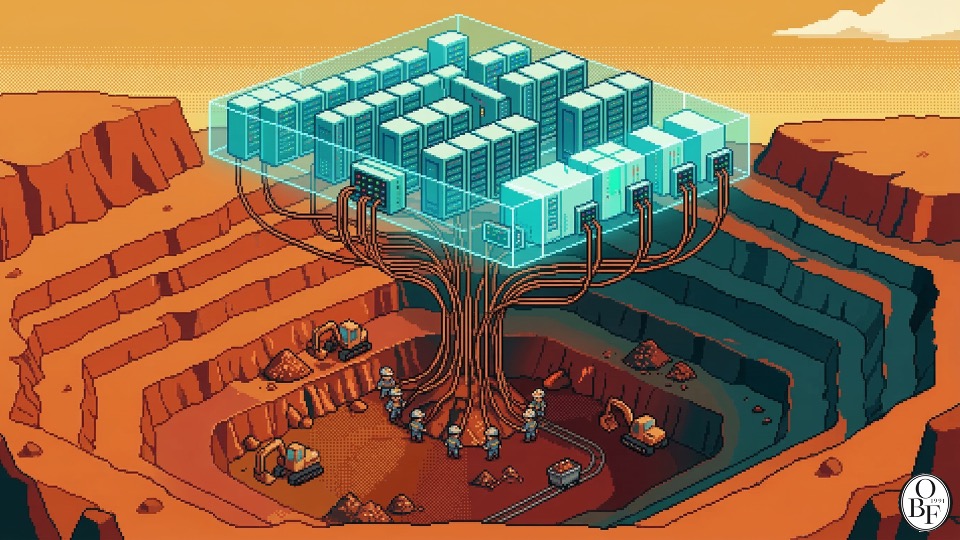
A report released by the IEA in April 2025 projected that global data center electricity consumption would more than double, from about 415TWh in 2024 to roughly 945TWh in 2030. That’s comparable in scale to Japan’s total annual electricity consumption at the time. 1TWh equals one billion kWh. This figure covers data centers overall, including non-AI services, and the IEA identified AI as the single largest driver of demand growth.
In the US, data centers are expected to consume more electricity by 2030 than the combined output of energy-intensive industries like aluminum, steel, cement, and chemicals production. That doesn’t mean they’ll surpass all of manufacturing’s electricity consumption. If data centers cluster geographically, the strain on regional power supply could intensify further.
Grid connections also take time. The IEA estimated that if related risks aren’t addressed, about 20% of planned data center projects could face delays. Building new transmission lines in developed countries can take 4 to 8 years. These projections will shift depending on the pace of AI adoption and efficiency gains, but they underscore a basic point: buying servers alone doesn’t mean you’re ready to operate them.
Can Copper Supply Keep Up With Demand
Expanding power infrastructure requires raw materials too. Copper is a prime example—it’s widely used in wiring and electrical equipment.
S&P Global’s January 2026 report Copper in the Age of AI projects global copper demand will rise 50%, from roughly 28 million tons in 2025 to 42 million tons in 2040. The analysis warns that without sufficient supply expansion, the world could face an annual shortfall of about 10 million tons by 2040.
Ramping up supply takes time. The report notes that new copper mines take an average of 17 years from discovery to full-scale production. Declining ore grades at existing mines add further strain—getting the same amount of copper now requires processing more ore than before.
And demand isn’t rising from AI alone. Data centers, transmission and distribution networks, electric vehicles, renewable energy installations, and defense industries are all competing for copper. S&P Global estimates that EVs use roughly 2.9 times more copper on average than internal combustion vehicles.
Copying a file one more time and producing one more ton of copper are governed by entirely different cost structures. Copper has to be mined, processed, and transported. That said, copper isn’t strictly irreplaceable in every application—some uses allow for substitute materials or designs that reduce copper consumption. Any supply-demand forecast should be read alongside these shifts, along with recycling trends and investment in new mines.
Even After Securing Mines, You Still Need Processing Facilities
What caught my attention in particular is processing and refining. Once you’ve secured the ore, you still have to separate out the elements you need and refine them to industrial-grade quality. If there are only a handful of places that can do this work, having mines spread across multiple countries doesn’t actually give you the flexibility to switch suppliers freely.
According to the IEA’s 2025 analysis, in 2024 production of the rare earths used in magnets—neodymium, praseodymium, dysprosium, and terbium—China accounted for roughly 60% of mining and about 91% of separation and refining. Its share of sintered rare-earth permanent magnet production was around 94%. These figures don’t cover all rare earths or all magnets lumped together.
Other minerals face similar issues. Of the 20 strategic minerals the IEA examined, China was the largest refiner in 19 of them, with an average market share of 70%.
In April 2025, China introduced export controls on certain rare earths and related metals and magnets. That October, it announced measures expanding the scope of controls to include related equipment and technology, as well as foreign-made products using Chinese-origin materials or technology.
That said, the measures announced in October were suspended through a November 7 notice, with implementation put on hold until November 10, 2026. As of March 2026, the April controls and the subsequently suspended measures need to be considered separately. The pattern of announcement followed by suspension is itself a source of uncertainty for companies trying to plan their supply chains.
Building refining facilities in another country doesn’t end with simply buying equipment. You need workers to run the process, raw materials, facilities to handle byproducts, and customers willing to buy the output. Diversifying supply sources means investing the time to build up all of these conditions.
Oswarld’s Lens
When I first read this column, I thought, “Is this just another ‘hardware matters again’ argument?” I’d heard similar claims during the chip shortage, and again when COVID-19 rattled supply chains.
What caught my attention this time was how the piece connects two things: AI making software development easier, and rising demand for physical infrastructure. If building things gets easier, demand for actually running services can grow too. And when that happens, I think the ability to secure power and materials on time will shape how fast a business can execute.
When tech companies define themselves purely as software companies, they tend to underestimate power, land, and equipment issues. But cloud services run on real data centers, and the hardware executing AI models needs electricity too. Even without owning physical infrastructure, a company can still feel the effects of supply shortages or price swings — through service fees and usage caps.
I don’t read this shift as meaning software’s competitive edge is disappearing. The ability to decide which problems to solve and build them into trustworthy products still matters, and will keep mattering. It’s more that we now also need to ask whether a company can secure stable power and equipment alongside that.
For Korea, I think the real question is how to leverage its accumulated manufacturing capability. Korea’s chip fabrication, Taiwan’s foundries, Japan’s materials and equipment — each has built strengths in a specific domain. That capability comes from years of hands-on experience and investment. The challenge is holding onto those existing strengths while securing a stable supply of the materials and power needed to keep them running.
What Belongs on the AI Business Timeline
If your company is scaling up an AI service, you need to check not just your models and talent, but also when you’ll be able to secure the equipment and power to handle the compute you’ll need. You don’t have to own a mine or a power plant yourself, but you do need to know how costs and schedules shift when supply gets delayed.
Going forward, I want to look at AI businesses through the lens of grid connection timelines, lead times for key equipment, and alternative supply sources too. I’ve become curious about just how big the gap is between the moment the code is ready and the moment the service can actually run reliably.
Looking at the fragment, I’ll check for accuracy against the Korean source.
The English draft looks accurate overall. Checking details: dates, numbers, links, and glossary terms all match. One issue: “graduated from the master’s program at Korea University’s Graduate School of Technology Management and a KMBA” means he graduated from the master’s program at Korea University’s Graduate School of Technology Management AND a KMBA — these appear to be two separate credentials, not “from the same school” redundantly stated. Let me verify this is accurate — actually it’s fine since KMBA is likely part of the same graduate school, but “from the same school” is an added clarification not in the source. This is a minor addition but doesn’t distort meaning. I’ll leave as is since it doesn’t violate any strict rules.
Everything else — headings, footnotes, links, images, numbers — matches exactly. No Hangul present. No numbers missing.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
- Paul Achleitner, Economic power is returning to the physical realm, The Economist, March 10, 2026. This is the column that sparked this piece.
- IEA, Energy and AI, April 2025. The source for data-center power-demand figures and grid-connection delay projections.
- S&P Global, Copper in the Age of AI: The Challenges of Electrification, January 2026. Covers copper demand and conditional shortage projections.
- Marc Andreessen, Why Software Is Eating the World, August 20, 2011. Explains how software-driven business models lowered the cost of starting a company.
- IEA, With new export controls on critical minerals, supply concentration risks become reality, October 23, 2025. Analyzes processing concentration by mineral and the export-control measures in effect at the time.
- Ministry of Commerce of China and General Administration of Customs, Announcement No. 70 of 2025, November 7, 2025. Confirms the suspension and duration of the measures announced in October.
Related issues
How Roblox's Small Games Reach Millions of Players
Fisch and Grow a Garden's success owes as much to Roblox's tools and recommendations as to gameplay itself.
BusinessWhy AI's Productivity Gains Don't Show Up in GDP Yet
Individual speed, organizational throughput, and economy-wide productivity are three different things worth separating.
BusinessWhen Meetings and Approvals Stall Work: Lessons from a 1944 Manual
Reading the OSS sabotage manual, I revisited the unnecessary meetings and approvals I've seen in consulting.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?