

Stripe Bought OpenRouter—Already Its Own Payment Customer
OpenRouter earns just 5.5% on credit top-ups, and Stripe was already processing those very payments before the acquisition.
BusinessThe payment processor collecting that 5.5% top-up fee was Stripe all along
On August 16th, Bloomberg reported that Stripe was acquiring OpenRouter. The price tag: over $7 billion, more than ₩9 trillion (~$6.5 billion). Most of the coverage framed it as payments finally making its move into AI.
But open up the pricing page of the company being acquired, and the story changes. OpenRouter doesn’t mark up token prices. What it actually earns is a 5.5% fee charged whenever users top up their credits. And the payment processor handling those top-ups was none other than Stripe.
In other words, Stripe just acquired a company that was already one of its own payment customers. More precisely, it bought both the top-up gateway through which AI usage payments flow and the 5.5% fee collected there.
The Price Tag That Grew 5.4x in 82 Days
OpenRouter is a company founded in 2023 by Alex Atallah, co-founder and former CTO of OpenSea. What it does is simple: one API key gives you access to more than 400 models across more than 70 providers. Switch from Claude today to DeepSeek tomorrow, and you don’t have to rewrite your code. It has 8 million users.
What stands out is how fast the price climbed. This past May, in its Series B round, it raised $113 million at a valuation of roughly $1.3 billion. Alphabet’s growth fund, CapitalG, led the round, with Sequoia, Andreessen Horowitz, and Menlo Ventures following. Then, 82 days later, the price tag read $7 billion. That’s 5.4x.
The gap widens further when you compare it to revenue. Sacra, a market-data firm, estimates OpenRouter’s annualized revenue1 at roughly $50 million as of March 2026 — a sharp jump from $19 million at the end of 2025, but still only around ₩70 billion (~$50M) in our currency. Divide the acquisition price by that revenue and you get roughly 140x. Given that software companies typically trade at 10x to 20x, this isn’t a price set on performance.
So what exactly was Stripe paying for?
The Revenue Isn’t Token Margin — It’s 5.5% of Every Credit Top-Up
Let’s break down OpenRouter’s revenue structure. The company doesn’t mark up token prices. Whether you’re calling Claude or Gemini, it bills you exactly at the rate the provider has posted. “No markup” is even the company’s core marketing line.
So where does the money come from? From charging up credits. Load $100 onto your card, and the actual usable balance is $94.50. They take 5.5% off the top. Fund it with crypto and it’s 5.0%, but the minimum fee is $0.80, so if you only top up $5, the effective rate climbs to 16%. Even in BYOK2 mode, where you bring your own API key, a 5% fee kicks in once you cross 1 million requests a month.
There’s no markup on the model usage fee itself — the cut is taken only at the top-up stage, when users put money in. And that money is collected upfront and held as a balance. This isn’t the revenue model of an AI company. It’s the revenue model of a payments company — more precisely, a prepaid-wallet operator.
OpenRouter left the evidence in its own writing. On June 9, 2025, a company blog post announced a simplification of its fee structure. It included this line:
We’re removing the flat $0.35 Stripe fee.
In other words, the old fee formula had literally been “a percentage plus a flat $0.35 Stripe fee.” OpenRouter had been selling its service with the Stripe fee displayed right there in its pricing, in plain sight. What’s now a single 5.5% line used to be those two separate lines merged together.
To sum up: what OpenRouter built over three years is model-routing technology, but in business terms, it’s a top-up-and-settlement gateway that AI usage payments pass through. 8 million users load credits onto their cards, and model-call costs are deducted from that balance. Until now, Stripe has processed those top-up payments on OpenRouter’s behalf. Stripe collected only the payment-processing fee — the 5.5% of every top-up went to OpenRouter.
Atallah has long called his own company “the Stripe of AI.” In the end, it was Stripe itself that ended up acquiring it.
This fee structure has four weaknesses
Let me lay out the counterarguments too. This 5.5% fee structure has several structural weaknesses.
First, the fee layered on top of pass-through3 shrinks along with model prices. The fee base is total spend, and AI model prices have kept falling for the past two years, with more declines likely ahead. Even if you run the same workload, if spend falls, the absolute dollar amount of that 5.5% falls too. UsagePricing, a pricing-analysis outlet, reads OpenRouter’s announced plan to shift BYOK fees from usage-based to flat subscription as a signal that the company itself knows about this weakness.
Second, competitors are already offering this fee at zero. Vercel’s AI Gateway advertises no token markup and no platform fee at all. Requesty charges 5%. In a market where rates are public, defending 5.5% means continuously proving the value of routing, fallback, and analytics.
Third, there’s the gateway’s chronic churn problem. As customers grow, they tend to contract directly with providers to cut out the middleman. The fact that OpenRouter attaches a fee even to BYOK mode is designed to capture revenue even from customers who are exiting this way. At the same time, it’s also an admission that such exits actually happen.
Fourth, neutrality is this product’s entire value proposition, and now it has an owner. Not being locked to any single model is the reason 8 million people use this service. Whether that neutrality survives the acquisition — and whether users will still believe it does — is a separate question.
Finally, this deal isn’t confirmed yet. Stripe’s position is that it “doesn’t comment on rumor or speculation,” and Bloomberg itself noted the final price could change. Demand for agent payments is also still thin. eMarketer’s estimate of $20.57 billion in 2026 US agentic commerce revenue is, after all, just an estimate.
So the point of this piece isn’t to say Stripe’s judgment was correct. It’s to pin down exactly what this company is betting its money on. As a caveat, this is commentary on industry structure, not grounds for an investment decision about any specific company or asset.
Reading This Alongside the PayPal Acquisition Attempt
What Stripe is after becomes clearer when you look at it alongside another recent acquisition attempt.
Stripe is currently pursuing an acquisition of PayPal together with the private equity firm Advent. In July, the two offered $60.50 per share—about $53 billion—and were turned down; they’re now renegotiating at a higher price. According to Reuters, the plan is for the two companies to co-own PayPal on an equal-equity basis, with no intention of breaking it up. If the deal goes through, combined annual processing volume would reach $3.7 trillion.
What Reuters flagged as the rationale behind this deal is interesting: reducing dependence on Visa and Mastercard. PayPal has its own balance system and direct bank-account rails that bypass card networks entirely. As long as you’re running transactions through a card network, you have to pay interchange fees4 to the card issuer.
Now layer this on top of everything Stripe has bought up over the past two years. Bridge, a stablecoin settlement company. Privy, which runs 110 million programmable wallets. Tempo, a payments-only blockchain built with Paradigm. With OpenAI, Stripe developed a payment protocol for agents, and at its Sessions event in April it unveiled an agentic commerce product suite—expanded to work with Meta and Google—along with an agent wallet for Link. It also demonstrated instant settlement by pairing Tempo with Metronome, a usage-based billing company, so that payment clears the moment value is delivered.
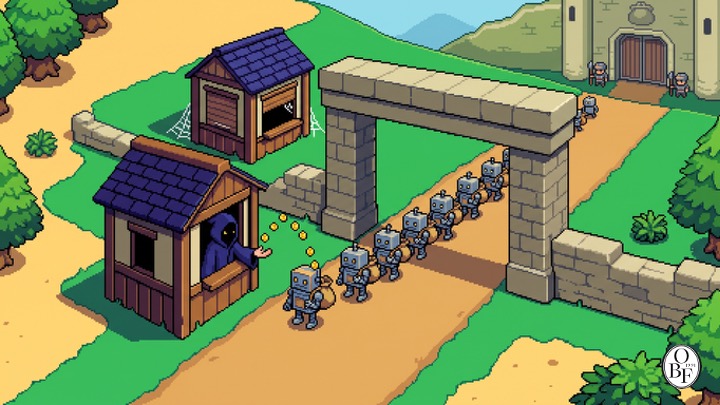
Stripe is now trying to lock down two payment rails at once: the rail where a human pays directly (PayPal), and the rail where an agent spends from a pre-funded balance (OpenRouter). And for both rails, it’s already lining up settlement methods that skip the card networks entirely.
For reference, Stripe processed $1.9 trillion in 2025—1.6% of global GDP. I think these two acquisition moves reveal exactly where the company is looking for its next growth opportunity.
Oswarld’s Lens
When I design pricing structures for GTM strategy, there’s a diagram I habitually sketch first. I draw a line tracing where the money flows, then mark a dot on that line showing exactly where our fee attaches. Even for the same product, the type of company you’re building completely depends on where that dot sits.
OpenRouter’s fee isn’t attached at the token-usage stage — it’s attached at the stage where users load credits. That’s why I think this company should be classified from the start not as AI infrastructure, but as a payments business. And Stripe would have known better than anyone exactly where that fee sat. It was handling settlement for those credit top-ups itself. For three years, Stripe was in a position to watch this company’s top-up transaction volume every single day.
Seen this way, the 140x multiple reads differently too. I don’t think it’s a price tag on $50 million in revenue — I think it’s the price of securing the toll booth that AI usage payments pass through. The value of a toll booth like this isn’t priced on the payment volume passing through it now, but on the volume expected to pass through it in the future. So whether this deal succeeds or fails depends less on routing technology than on whether agents actually end up spending more money than humans do.
Nobody knows the answer to that yet. My read is that Stripe didn’t buy this out of conviction — it staked out a position in advance, in case agent payments do scale up. If that bet is wrong, the returns may fall short of the acquisition price. But if the market does grow and Stripe hadn’t gotten in, it would have handed this payment channel to a competitor.
Here’s how this applies in practice. If you’re building an AI product, check whether your cost sheet lists only the token price. Once you add gateway fees and foreign card conversion costs, the real burden runs 5-8% higher than what’s on the sheet. That fee band — that’s exactly what Stripe paid ₩9 trillion (~$6.5B) for.
Closing
Let me sum up in three points.
First, OpenRouter’s revenue isn’t a token margin — it’s 5.5% of credit top-ups. The company itself announced it was scrapping the “flat $0.35 Stripe fee,” which tells you this was a payment-fee structure from day one.
Second, the $7 billion valuation is roughly 140 times estimated revenue. I read that as a number priced not on current earnings but on the volume of payments expected to flow through this top-up gateway going forward.
Third, this deal should be read as a package with the PayPal acquisition attempt. That said, nothing is confirmed yet, and pass-through fees shrink as model prices come down.
If you only do one thing this week, go through the bill for whatever AI service you’re using and add up every line item that isn’t the token charge. That total is the slice of fees that Stripe just put a price tag on with this acquisition.
💬 Have you ever switched from a gateway to a direct contract? Tell me in the comments at what spending level the math flipped in your favor. I’ll gather these cases and follow up in a piece on AI cost structures.
📨 If you have a colleague digging into AI costs or payment infrastructure, please share this piece with them.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- OpenRouter, “Simplifying Our Platform Fee”, 2025.6.9. ··· This is today’s decisive piece of evidence. The line “we’re eliminating the flat $0.35 Stripe fee” is right there. One pricing announcement, three months before the acquisition, explains the entire acquisition logic.
- Bloomberg, “Stripe Finalizes Deal to Acquire AI Startup OpenRouter for Over $7 Billion”, 2026.8.16. ··· The original report on the acquisition. Worth reading alongside the caveat that the final price could still change.
- TechCrunch, “Stripe will reportedly acquire AI gateway startup OpenRouter for $7B+”, 2026.8.16. ··· Lays out the $113 million Series B, 8 million users, and Atalla’s “Stripe for AI” remark.
- Sacra, “OpenRouter revenue, valuation & funding” ··· The source for the estimated $50 million ARR, the annualized run rate. Keep in mind it’s an estimate.
- UsagePricing, “OpenRouter Pricing Blueprint”, 2026.6.10. ··· Traces the evolution of the pricing structure through Wayback Machine snapshots. This is where the sharpest counterargument — “fees on top of pass-through shrink along with model prices” — is laid out.
- Engadget, “Stripe is reportedly in talks to buy PayPal”, 2026.8.15. ··· Contains the $60.50-per-share figure, the $3.7 trillion in annual processing volume, and the discussion of reducing dependence on Visa and Mastercard.
Background
- Stripe, “Stripe’s 2025 Annual Letter”, 2026.2. ··· Covers the $1.9 trillion in processing volume and the five-stage breakdown of agentic commerce. The fastest way to see how far the company itself is willing to imagine this going.
- Fortune, “Visa to expand card partnership with Stripe’s Bridge to over 100 countries”, 2026.3.3. ··· Covers Bridge’s card expansion. Particularly worth reading for Bridge’s CEO saying “agent transactions have a different texture than card networks.”
Related past issues worth reading

📝 Glossary
Footnotes
-
Annualized Run Rate (ARR): A figure obtained by multiplying the most recent month’s or quarter’s revenue by 12 or 4 to project a full year. It shows how fast a fast-growing company is moving right now, but it isn’t money actually earned over a full year. ↩
-
BYOK (Bring Your Own Key): Using an intermediary platform but paying the model usage fees directly through your own account. You pay the toll, but you fill up the gas with your own card. ↩
-
Pass-through: Billing the underlying cost straight through with no markup. Revenue instead comes from a separate fee, which means that when the underlying cost falls, the base on which that fee is charged shrinks too. ↩
-
Interchange fee: The fee that passes from the merchant side to the card issuer whenever a card payment occurs. It’s unavoidable as long as a transaction runs through a card network, which makes it the biggest motivation behind attempts to route around card networks. ↩
Related issues
Why Legal Adopted AI Agents First, Not Engineering
Legal's Codex usage jumped 108x since February, far outpacing engineering's 5x—and Google's first industry AI targets finance and law.
BusinessGoogle's Preferred Source Button Hides Follower Counts
Google's new preferred-source button could boost publishers, but they can't see who's actually clicking it.
BusinessSK Hynix Leverage ETF's First Day: Trading Volume Fell by Two-Thirds
Prices surged under new leverage ETF rules, but trading volume cratered—proof that demand, not stability, was curbed.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?