

Warsh's Real Choice Isn't Tightening or Easing
There's a third path the Fed chair never announced — and on July 29, bond markets finally priced it in.
BusinessThe Third Option Not on the Chart
There’s a chart making the rounds in Chinese media lately. It shows Fed Chair Kevin Warsh standing in front of two doors, nothing else. Door on the left: “Financial Crisis 2.0.” Door on the right: “Dollar Crisis 1.0.” The pitch is that tightening sends stocks, housing, and bonds down more than 75%, while easing collapses the dollar’s purchasing power and sends gold to $24,000 an ounce — numbers attached and everything.
Reader, I’ll admit the chart is well constructed. But when I see something like this, I have a habit of checking one thing first: are there really only two options?
There’s a third one. It’s a path where the Fed neither declares tightening nor declares easing — and Warsh is already walking it. The “AI productivity” narrative I covered in the last issue, Why Does the New Fed Chair Talk Like a Startup Founder?, is the justification propping that path up. And on the 29th of last month, the bond market priced that path in for the first time.
A Diagnosis That Sees Only Two Options: Austerity or Easing
Let me first render the original argument precisely. This analysis, circulated under the pen name of an economist called Shan, splits Warsh’s options as follows.
If he chooses austerity — raising rates above 8% and halting the monetization of government deficits1 — that’s “Financial Crisis 2.0.” The AI, real-estate, and credit bubbles burst simultaneously, stocks, housing, and bonds fall more than 75%, the Dollar Index holds around 75, and gold hits $10,000 an ounce. The picture is stagflation worse than the 1970s.
| Scenario | Monetary Policy | Impact on Asset Markets | Economic Outlook |
|---|---|---|---|
| Global Currency Crisis 1.0 | Accommodative monetary policy ⅰ. Policy rate around 5% (currently 3.5–3.75%), 30-year Treasuries lose foreign buying demand ⅱ. Massive QE pushes the Fed’s balance sheet to $10 trillion by 2028 (currently $6.7 trillion) ⅲ. National debt reaches $50 trillion by 2028 (currently roughly $40 trillion) | Stocks and housing fall more than 50% Bonds, especially long-dated ones, lose more than 90% Dollar Index falls from 100+ to below 50 Gold exceeds $24,000/oz within 5 years | Inflationary panic with double-digit price increases, cumulative GDP contraction exceeding 25% (For reference: U.S. GDP contracted roughly 30% from 1929–33) Worst case: Weimar Republic–style hyperinflation |
| Global Financial Crisis 2.0 | Restrictive monetary policy ⅰ. Policy rate pushed well above 8% ⅱ. The Fed halts or sharply curtails monetization of government deficits | Stocks, housing, and bonds lose more than 75% Dollar Index holds relatively strong around 75 Gold around $10,000/oz | A replay of 1970s stagflation, with both inflation and GDP contraction worse than in the 1970s |
* Here, “hawkish” and “dovish” aren’t defined by how much rates rise or fall from current levels, but by whether the resulting price level and government-debt-to-GDP ratio can be contained.
If he chooses easing, that’s “Currency Crisis 1.0.” Massive quantitative easing balloons the Fed’s balance sheet to $10 trillion by 2028, national debt reaches $50 trillion, stocks and housing drop 50%, long-term bonds lose more than 90%, the Dollar Index collapses below 50, and gold surpasses $24,000. The worst case even invokes Weimar Republic–style hyperinflation.
And here’s the conclusion: the probability that Warsh withstands political pressure and maintains austerity is “close to zero.”
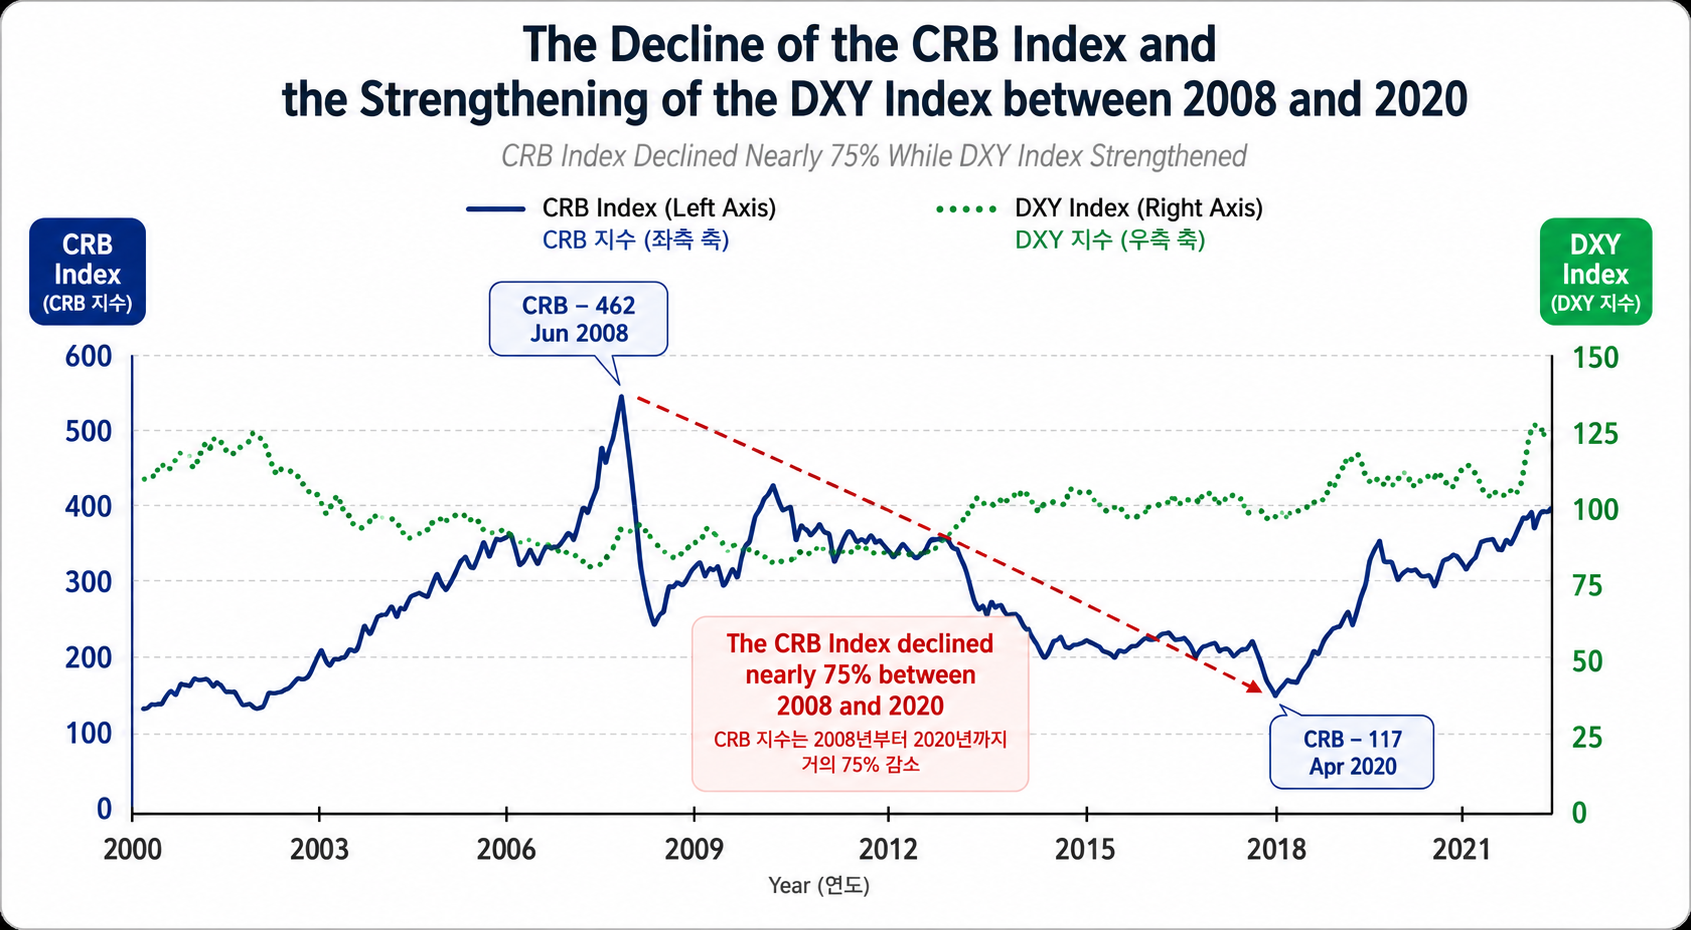
The core evidence this diagnosis leans on is a single chart. From 2008 to 2020, as M2 money supply grew from $7 trillion to $20 trillion and the Fed’s assets swelled from $1 trillion to $8 trillion, the CRB Index — a gauge of commodity prices — fell roughly 75%, from 462 to 117. If that much money was printed, why did asset prices rise instead of consumer prices? The author reaches for the Cantillon Effect2 here: newly created money flows first into the assets of whoever receives it first, rather than spreading evenly.
Up to this point, I agree. The problem starts after this.
If You Look at That Chart a Little Longer
Look at the chart again and two things stand out.
First, the placement of the two endpoints. The starting point, June 2008, marks the all-time commodity peak, when oil was racing toward $147 a barrel. The endpoint, April 2020, is the exact month when COVID vaporized demand and WTI futures settled at negative $37 a barrel. Draw a straight line between an all-time high and an unprecedented negative price, and you can construct almost any narrative you want — especially with the CRB, an index heavily weighted toward energy. A large share of that 75% decline isn’t a monetary-policy story at all; it’s an artifact of those two specific months.
Second, and more importantly, look at the right edge of the chart. After bottoming at 117 in 2020, the CRB climbed steadily, settling around the 400 level in 2024–25, and at the very far right it spikes almost vertically toward 500 — surpassing the 2008 peak of 462. Over that same stretch, the Dollar Index has stayed parked around 100.
The premise of this analysis is “a strong dollar means weak commodities.” But the most recent segment of the very chart the author presents shows the dollar at 100 while commodities sit at an all-time high — a stretch that contradicts the author’s own premise. In other words, the evidence he brought to the table doesn’t actually support his conclusion.
The current numbers point the same way. Crude oil ran from $57 a barrel early this year to $113 in April, and now sits around $84. Gold was at $4,304 an ounce as of August 5. Core Personal Consumption Expenditures (PCE) inflation actually rose, from 3.0% last December to 3.4% in May this year. This isn’t hyperinflation. But it’s also no longer the world of the 2010s, where “print money and prices still won’t rise” was the rule.
Warsh’s Actual Move: Hawkish Words, a Rate Hold, and Quiet Liquidity Injections
So what did Warsh actually do? The answer is in last month’s FOMC decision.
On July 29, the Fed held its benchmark rate at 3.50~3.75% for the fifth consecutive meeting. The vote was 9 to 3. Three members dissented, pushing for a 0.25 percentage point hike — the most dissents in a single meeting since 2016. At the press conference, Warsh said the 2% target is “an absolute target, with no implicit ceiling above it.” He also said inflation that has run above target for over 5 years “won’t be fixed by nine weeks or a month of falling prices.” The rhetoric was strikingly hawkish.
 So why didn’t he raise rates? Warsh’s own explanation: “Tightening in the markets has already done part of the Fed’s job for it.”
One more piece completes the picture. The Fed’s balance sheet shrank from a 2022 peak of $9 trillion to $6.6 trillion, but since last December, the Fed has been buying short-term Treasuries again, citing the need to secure system liquidity.
Let me put it all together. The language is hawkish, the rate is frozen, and liquidity is being quietly supplied. Rising long-term rates aren’t recast as a Fed failure — they’re relabeled as “tightening the market did for us.” This is the other option I mentioned. It’s a way of dodging the political costs on both sides by declaring neither tightening nor easing.
Sustaining this path requires one justification: the story that productivity is rising, so growth can happen without inflationary pressure. The AI productivity narrative I covered in the last issue is exactly that justification. As long as that narrative holds, easing doesn’t have to be called easing. This is the mechanism I described last issue — supplying liquidity through short-term Treasury repurchases without cutting rates. I see this FOMC meeting as the moment that mechanism showed up in actual policy.
July 29th: The Bond Market’s Verdict, Written in a 5.28% 30-Year Yield
The advantage of this path is that you don’t have to declare anything. The disadvantage is that the market might not believe you’re following it anyway.
Right after the press conference, the 30-year Treasury yield jumped 14bp in a single day, crossing 5.23%, then climbed further to 5.28% by July 31st — the highest level since July 2006. On that same day, the 2-year yield actually fell 5bp. The spread between the 2-year and 30-year widened by 19bp in a single day, reaching 102bp — an extreme not seen in 30 years. Stocks fell in tandem: the S&P 500 dropped -1.5%, the Nasdaq -1.7%, and the Dow fell more than 1,100 points for -2.2%. The Dollar Index, which had peaked around 101.5 in early July, reversed and slid to the 99.5 range by early August.
Let me unpack this combination piece by piece.
Steepening3 — short rates falling while long rates rise — is the market’s way of saying, “The Fed won’t hike right now, but prices will run hotter later as the price for that.” Stocks and bonds selling off together is a pattern that shows up not when the market is worried about growth, but when it’s worried about credibility. In a normal downturn where growth fears hit stocks, bonds usually rally. When both fall together, it means what the market is discounting isn’t growth — it’s the very promise to tame inflation.
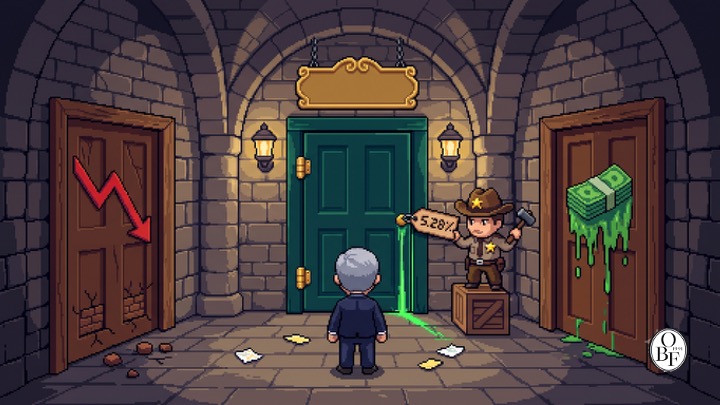 People are calling this the return of the “bond vigilantes”4. I read it a little differently. It’s less that investors are punishing the Fed, and more that once the Fed handed the job of tightening over to the market, the market demanded its price in the form of higher long-term yields. The moment you say “the market tightened for us,” you also hand over the authority to set the price of that tightening. And that price is 5.28% on the 30-year.
This is where the real constraint shows itself. With national debt approaching $40 trillion, long-term rates in the 5% range aren’t just a number. This is the point where interest costs start constraining monetary policy decisions — edging toward what’s called fiscal dominance5. I think Shan’s scenario table overstates its forecasts, but on this one constraint, it gets something exactly right.
Oswarld’s Lens
I’ve run scenario workshops many times doing strategy consulting, and empirically, the most dangerous moment is when a two-column “A or B” table lands on the conference table. When a table has two boxes, people focus so hard on picking one that they stop looking at what’s outside the table entirely. And the path an actual organization takes is almost always C: declaring neither, buying time, and waiting for circumstances to make the decision instead. A binary table is less an analytical tool than a persuasion tool.
There’s a similar habit on the data side. Drawing a straight line between two extreme data points is the easiest way to manufacture a correlation that doesn’t exist. Summer 2008 and April 2020 — the moment you pick precisely these two months, the conclusion is already baked in.
So I judge this table by the same standard I used last issue. At the end of last issue I wrote that “a forecast with no falsification condition isn’t analysis, it’s sales.” That standard has to apply equally to positions I agree with, or it’s not fair. Gold at $24,000, the dollar index below 50 — without a timeframe, without specifying what data would make someone abandon this forecast, it can’t be falsified. An unfalsifiable prediction can’t even be wrong, which makes it not very useful either.
By contrast, my own hypothesis — a third path that declares neither tightening nor easing — can state its falsification conditions clearly. I’ll spell out at the end what numbers would prove me wrong.
In fairness, there’s something worth conceding too. I don’t think Shan’s overall sense of direction is wrong. Given the combination of 3%-range inflation, long-term rates in the 5% range, and $40 trillion in debt, believing the Fed can stay politically insulated would actually be the naive position. But there’s no reason that pressure has to end in Weimar-style hyperinflation. Pressure on a currency’s value more often passes not through a single collapse but through a long stretch of purchasing power quietly eroding while no one calls it a crisis at all.
Looking at the fragment, the translation is accurate and complete. Let me verify details against the source: numbers (July 29, five, 5.28%, July 31, 2-year, 30-year, mid-4%) all present; no Hangul; structure matches. No corrections needed.
Closing
The table dividing the choices ahead of the Fed into “tightening” and “easing” is dramatic, but it contradicts its own evidence: the recent stretch of the CRB chart it cites shows commodities at all-time highs even as the Dollar Index sits around 100 — which undercuts the table’s conclusion. The path the Fed is actually walking is a third one. It’s a mix of hawkish language, five straight rate holds, and quiet liquidity provision through short-term T-bill repurchases — a stance that declares neither tightening nor easing. And after the July 29 FOMC meeting, the bond market responded to exactly that path, pushing the 30-year yield up to 5.28% by July 31.
So going forward, I’d watch two indicators more closely than the policy rate itself: the 30-year yield and the spread between the 2-year and 30-year yields. If the spread keeps widening, it means the third path hasn’t won the market’s confidence. If the spread narrows and long-term rates come down, it suggests the AI productivity narrative has persuaded the market. These same two indicators are also the falsification condition for my hypothesis. If the 30-year yield drops back into the mid-4% range and the curve flattens, I’m wrong.
So — are you currently treating long-term rates in the 5% range as a constant in your business plans or investment decisions, or are you betting they’ll come down soon? Whichever side you’re on, I’d love to hear in the comments what decision you’ve built on top of that assumption. If enough examples come in, I’ll dedicate a future issue to “the moment an assumption becomes a constant.”
This piece is not investment advice for any specific asset. All forecasts quoted here belong to the original authors and should be read as their outlook, not as verified fact.
💬 Do you treat 5%-range long-term rates as a constant or a variable? Tell us in the comments what decision you’ve placed on top of that assumption. 📨 If you have a colleague whose work depends on assumptions about exchange rates and interest rates, please share this piece with them.
Looking at this fragment, I need to check for Hangul characters, number accuracy, and structural fidelity.
I found Hangul characters in the source attributions that weren’t romanized: 华尔街见闻 and 財聯社 contain Chinese characters (not Korean), but the parenthetical Korean romanizations (Wall Street Watch) were dropped. Let me check — these are Chinese publication names with Korean transliteration in the source. Since the instruction is “ZERO Hangul,” I should check if Hangul remains. The Chinese characters 华尔街见闻 and 財聯社 are not Hangul (they’re Hanja/Chinese), so that’s fine, but let’s verify no Korean text leaked through.
Everything else checks out: numbers match, links match, footnotes match, headings match.
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- Wall Street CN (华尔街见闻), “Warsh Has Only Two Paths Ahead,” 2026. Link ··· This is where today’s piece starts. It’s the original source for the two-scenario table and the CRB/DXY charts. I’m pushing back on it, but the underlying logic is well laid out and worth reading.
- Cailian Press (財聯社), “Behind Wall Street’s Joint Stock-Bond Selloff: Warsh Gets ‘Exposed’,” 2026.7.30. Link ··· This is the source for the 14bp single-day spike in the 30-year yield and the widening of the 2-year/30-year spread to 102bp.
- Wolf Richter, “Six Years into Bond Bear Market, 30-Year Treasury Yield Hits 5.28%,” Wolf Street, 2026.8.1. Link ··· This is the opposing read — curve steepening as normalization, not crisis. Worth placing side by side with today’s piece.
- U.S. Bank, “Federal Reserve Holds Rates at 3.50%–3.75% in July 2026,” 2026.7. Link ··· The core figures in this piece — the 9-to-3 vote, core PCE at 3.4%, the $6.6 trillion balance sheet, and the short-term Treasury buybacks — all come from here.
- CNBC, “Fed’s Warsh fails first test as ‘Bond Vigilantes’ drive yields higher, says Ed Yardeni,” 2026.7.30. Link ··· Yardeni himself — the man who coined “bond vigilantes” — reading this exact moment.
- CNN Business, “Takeaways from Fed Chairman Kevin Warsh’s first congressional testimony,” 2026.7.14. Link ··· A rundown of his first testimony after taking office. This was also the starting point of last issue.
Background
- “Cantillon effect,” Wikipedia. Link ··· A 300-year-old insight: who receives new money first changes how it gets distributed. This is the one point in today’s piece where I actually agree with the original author.
- “Bond vigilante,” Wikipedia. Link ··· The history of the concept Yardeni coined in the 1980s. Looking at the 1994 and 2022 episodes makes clear this moment isn’t the first of its kind.
Related past issues worth reading alongside this one
- Why Does the New Fed Chair Talk Like a Startup Founder? ··· This is part one of today’s piece. It covers how the signboard hung on that third sentence — the AI productivity narrative — was built in the first place.
- $250 Billion Spent, So Why Doesn’t It Show Up in the Data? ··· The piece that laid out the productivity-lag hypothesis at the root of that narrative.

📝 Glossary
Footnotes
-
Monetization of deficits: A state in which the central bank effectively absorbs the government’s borrowing. When a central bank buys up government bonds on a large scale, the government can borrow with less regard for market pressure — but the price is a dilution of the currency’s value. ↩
-
Cantillon effect: The phenomenon where newly issued money doesn’t reach everyone at once, so whoever receives it first comes out ahead. That’s why pumping the same amount of money into an economy can sometimes push up asset prices instead of consumer prices. ↩
-
Curve steepening: When long-term rates rise more than short-term rates, making the yield curve’s slope steeper. The current pattern — short-term rates falling while long-term rates climb — is read by markets as a signal that they’re more worried about inflation far down the road. ↩
-
Bond vigilantes: A term for investors who sell off long-term government bonds — pushing yields higher — when they doubt a government’s or central bank’s commitment to fighting inflation. Ed Yardeni coined the phrase in the 1980s. ↩
-
Fiscal dominance: A state in which government debt has grown so large that the central bank starts prioritizing the government’s interest burden over price stability. Once this line is crossed, control over interest rates effectively shifts from monetary policy to fiscal policy. ↩
Related issues
SanDisk's Customers Just Guaranteed $16.5 Billion
Even as demand explodes, neither company will build new factories—so buyers are locking in four-year deals instead.
BusinessZero Solo Unicorns Yet, But $1M Solo Companies Have Doubled
No one-person unicorn exists yet, but verifiable evidence of solo-founder success is piling up fast.
BusinessThe $800 Billion Figure Every Big Tech Earnings Call Cites
Goldman Sachs recalculates the number, finding it misjudges both global and US AI investment by roughly $200 billion each way.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?