Silicon Valley Crowns Imperial CEOs Again
Anthropic, SpaceX, and Meta made the same bet this year: absolute founder control over shareholder democracy.
BusinessA Once-Taboo Word Returns
Reader, imperial leadership was once considered taboo in the startup world. Waterfall was deemed the worst approach, while lean, agile, and reciprocal leadership were celebrated as the ideal. Eventually, people even took it to extremes like servant leadership1.
Yet today, we are living in the era of the most imperial CEOs.
Last week on October 26, Anthropic made its S-1 registration statement2 public—an IPO that could become the largest in history. Yet the most widely cited detail in the filing was not its revenue, but its voting power. While the 7 co-founders each hold an economic stake of around 2%, together they command 50.1% of the voting rights at shareholder meetings. SpaceX, which went public in June, handed 85.1% of its voting power to Elon Musk alone. On October 19, Meta’s board approved the creation of non-voting shares specifically designed to protect Mark Zuckerberg’s control. The Wall Street Journal dubbed this trend the “era of the imperial CEO.”
And what about the companies that have succeeded so far—the ones that ‘endure’ and ‘thrive’ over the long haul? Well, look at that. Every single one of them is imperial. Is being democratic really the right choice after all?
Today, with this question in hand, we’ll examine what these 3 companies actually wrote in their filings, and what the data stacked on the other side reveals.
The Structures Three Companies Chose in the Same Year
All three companies rely on dual-class voting structures,3 but their architectural blueprints look quite different. Let us start with a side-by-side comparison:
| Company | Founder Mechanism | Founder Voting Power | Checks and Balances |
|---|---|---|---|
| Anthropic | 1 share of special stock (Class F) held by founders’ LLC | 50.1% fixed across 7 founders | Long-Term Benefit Trust (LTBT) elects 4 of 7 board seats |
| SpaceX | Class B stock with 10 votes per share | Musk holds 85.1% | Virtually none |
| Meta | Existing dual-class structure + creation of non-voting Class C | Zuckerberg holds ~60% | Special board committee, shareholder litigation |
Anthropic is the most unusual of the three. An LLC formed collectively by its 7 founders holds exactly 1 share of Class F stock, which carries a permanent 50.1% majority of voting power on general corporate matters. It holds zero economic rights. That means no matter how many Class A shares public investors accumulate, their combined voting power cannot exceed 49.9%. This arrangement remains in effect as long as at least 3 of the 7 founders maintain a designated equity threshold. Crucially, however, a board majority is elected not by the founders, but through Class T shares held by the Long-Term Benefit Trust (LTBT). Anthropic functions less like a personal monarchy and more like a shared-governance compact between founders and a purpose-driven trust. In regulatory filings, the company explained that the founder group is uniquely suited to steward its mission. Under Nasdaq rules, it qualifies as a controlled company,4 exempting it from requirements such as an independent nominating committee.
SpaceX takes the opposite approach, concentrating absolute authority in a single person. Musk owns 12.3% of Class A stock and 93.6% of high-vote Class B stock (10 votes per share), yielding 85.1% total voting power. Ousting Musk as CEO or chairman requires a majority vote of Class B shares—and the only person capable of casting that majority is Musk himself. Tesla went public under a single-class structure, and Musk has repeatedly voiced anxiety over losing control to activist shareholders ever since. SpaceX is his definitive countermeasure.
Meta’s latest maneuver comes with fascinating timing. On November 3, California voters consider Proposition 40, a ballot measure proposing a one-time 5% tax on billionaire net worth. Zuckerberg warned the board that if the measure passes, he would have to liquidate voting stock to pay the tax bill, diluting his voting power from 60.6% down to roughly 53%. He even raised the prospect of leaving the state entirely. In response, the board approved a plan to distribute non-voting Class C shares to all stockholders in January 2027—effectively a 2-for-1 split. Zuckerberg can immediately sell up to 20% of his newly issued Class C stock (about 10% of his total economic interest), while committing in exchange to remain in California or near company headquarters for 8 years. Meta went out of its way in regulatory filings to stress that board members challenge Zuckerberg candidly rather than acting as a rubber stamp. Even so, on October 27, a public pension fund filed suit in Delaware Chancery Court to block the transaction. The complaint contends that because the tax assesses residency as of January 1, 2026, relocating now would provide zero relief anyway—making the threat to leave an empty pretext.
Investors Placed the Crown
What makes this scene so striking is that just a generation ago, the exact opposite declaration was made. In January 1993, Fortune ran a cover story titled “The King Is Dead,” chronicling the fall of the imperial CEO and the rise of shareholder primacy. The piece captured a trend where shareholders’ voices were growing louder than those of CEOs. On Wall Street, arguments over stock structures that stray from “one share, one vote” have raged for more than 100 years.
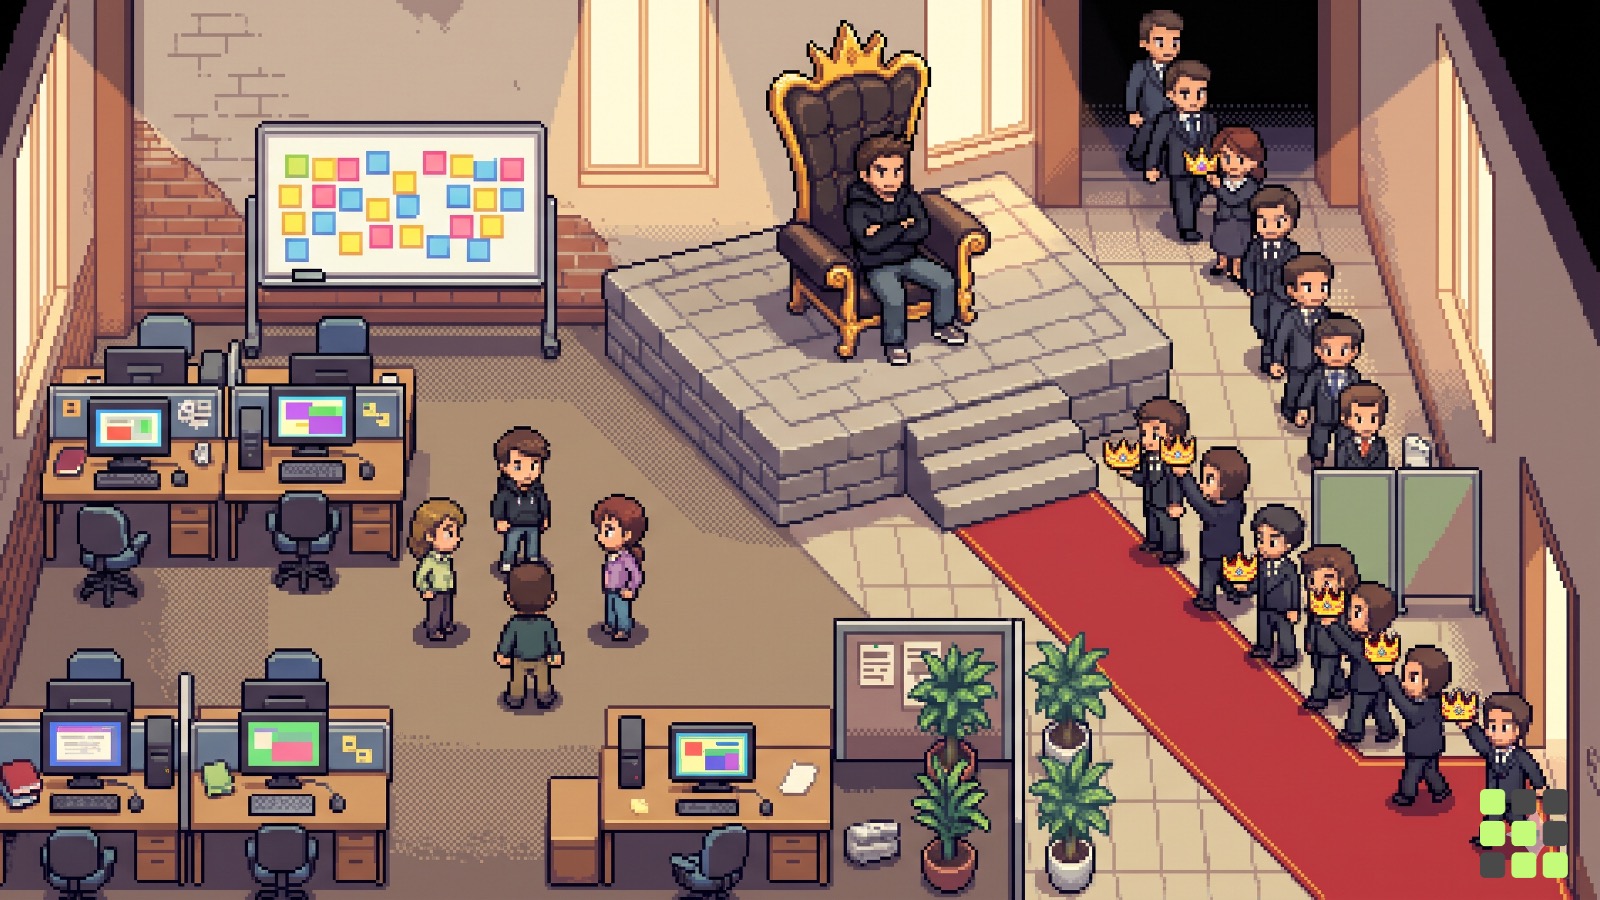
The most recent major clash came in 2017. When Snap offered only non-voting shares in its public debut, S&P Dow Jones Indices barred newly listed companies with multi-class share structures from benchmarks like the S&P 500. The following year, then-SEC Commissioner Robert Jackson used a speech at UC Berkeley School of Law to advocate mandatory sunset provisions on dual-class voting rights. His argument was straightforward: asking public investors to put eternal trust in corporate royalty runs counter to American values.
That push failed. S&P dropped its ban in 2023, and SpaceX rode retail investor enthusiasm to become the largest IPO in history. Meanwhile, Silicon Valley fell in love with the phrase “Founder Mode,” coined in a 2024 essay by Paul Graham. The thesis was that founders who dive directly into the operational details outperform professional managers who delegate power while walking on eggshells around boards and shareholders. As The Wall Street Journal observed, investors simply seem eager to hand control over to CEOs they like.
Nor is this preference without empirical backing. A study by Martijn Cremers of the University of Notre Dame and his coauthors, which paired and compared US public companies from 1980 to 2017, found that dual-class firms boasted valuation metrics (Tobin’s Q5) that were, on average, 13% higher than those of matched single-class peers at the end of their first public year. This premium was even more pronounced in companies where founders remained at the helm. The intuition that markets will pay up for a founder’s vision and drive holds water—at least in the early years on the public market.
Same Weapon, Different Outcomes: Meta and Snap
Meta illustrates vividly what corporate control actually makes possible. Since its 2012 IPO at $38 per share, Meta’s stock has surged more than 1,500%. Of course, the trajectory was hardly a straight line. The stock rode a rollercoaster while Mark Zuckerberg poured billions of dollars into the unproven tech of the metaverse. Yet because he held uncontested control, he was able to push that bet through—and when he pivoted toward AI, he moved with that same relentless momentum, dangling $100 million compensation packages to recruit top talent.
There are other companies built on the exact same structure. Armed with 53.1% of the voting power, Snap’s Evan Spiegel has spent years obsessing over smart glasses. Spiegel views these devices as the next gateway to the digital world, but consumer reception remains tepid. In March this year, activist investor6 Irenic Capital acquired an approximate 2.5% stake and demanded that Snap spin off or shut down its smart glasses business. Irenic pointed out that Snap had already sunk more than $3.5 billion into the venture. Spiegel refused, and in June unveiled a $2,195 pair of AR glasses called Specs. According to The Wall Street Journal, Snap’s shares trade nearly 70% below their 2017 IPO price.
There is an essential point to make here. Structurally, Meta’s bet on the metaverse and Snap’s bet on smart glasses are the exact same decision. In both cases, a founder staked the future against the vocal objections of investors. What separates “conviction” from “stubbornness” is not the decision when it is made, but the outcome after the fact. While long-thriving imperial enterprises naturally catch our eye, the companies that started with the exact same structure and quietly faded away rarely make it onto our radar.
The Premium Came with an Expiration Date
There is a second half to Cremers’s study. The premium observed in the early years post-IPO steadily eroded over time, on average vanishing or even turning into a discount within 6 to 9 years after listing. The researchers interpreted this as the founder’s vision either reaching realization or losing steam: the benefits of leadership faded, while the costs of unchecked management mounted. That led them to propose a sunset clause7, under which ordinary shareholders vote on whether to extend the multi-class arrangement after a predetermined period. Citing this study, the Council of Institutional Investors (CII) petitioned the New York Stock Exchange and Nasdaq in 2018 to mandate a 7-year sunset post-IPO.
This is precisely where The Wall Street Journal finds cause for concern. If the leader gets it right, investors make a fortune; if the leader gets it wrong, there are almost no levers to correct course. And these very names are increasingly filling the portfolios of 401(k)s and public pension funds. Even those who never bought the stock directly are already along for the ride under this governance regime.
South Korea wrote an answer to this dilemma directly into its statutes. Starting November 17, 2023, founders of unlisted venture enterprises became eligible to receive dual-class shares carrying up to 10 voting rights per share. The conditions, however, are tightly drawn. The founder must be an original promoter who serves as an executive director; they must have held at least 30% of the equity since inception; and that stake must have diluted below the threshold because of large-scale external investment. Issuance requires approval from 3/4 of voting shares, and the structure’s term cannot exceed 10 years. Upon an IPO, the stock converts to common shares after 3 years, and it converts immediately if the founder leaves the board or transfers the shares. On core governance matters like director compensation, auditor appointments, and dividend payouts, dual-class shares carry only 1 vote per share.
In short, the Korean framework is designed around “for how long and on which matters” rather than an open-ended “should we empower the founder?” Anthropic’s S-1 contains no such fixed expiration date. So long as 3 or more founders remain, that 50.1% control holds—which is why U.S. media noted that this reign could easily last for decades.
Oswarld’s Lens
Watching this trend play out forced me to dust off a long-held piece of conventional wisdom. For years, the startup world treated imperial leadership almost as a taboo. Waterfall was obsolete, lean and agile were righteous, and at the end of that spectrum sat servant leadership. Yet today, the companies the market values most richly are precisely the ones where founders retain an iron grip. The same holds true when you look at companies that have endured and prospered over the long haul. Which brings us back to the question: Is a democratic approach truly always the right one?
Still, it is worth asking whether these two conversations are happening on the same plane. Agile and servant leadership are about how teams work and learn; dual-class shares are about who has the power to stop the CEO when things go wrong. Indeed, Dario Amodei of Anthropic—a company with one of the most fortified governance structures in tech—has said he spends up to 40% of his time tending to company culture. Holding final decision-making authority and imposing a top-down way of working day-to-day are not necessarily the same thing.
Framed that way, the real question shifts from “democracy versus monarchy” to “for how long, and for which decisions?” The academic finding of 6–9 years post-IPO, alongside the South Korean statutory limits of 10 years total duration and 3 years post-IPO, offers one tangible set of answers to that very question.
Closing
Founders didn’t crown themselves. The crown was placed on them because index providers opened the gates, retail investors lined up, and boards of directors signed off.
The Wall Street Journal closed its piece on this note: ultimately, buying those shares is casting a vote for their rule. Shareholders in Meta and Snap cast the exact same ballot. Only the outcomes differed.
💬 Among the companies you’ve worked for or with, did the smoothest-running ones concentrate decision-making in a single person, or distribute it among many? Leave a one-line comment below.
📨 If you have colleagues preparing to launch a startup or reviewing a term sheet, please share this post with them.
Already a subscriber? Sign in to join the conversation


References & Further Reading
Primary sources
- The Wall Street Journal, “We’re Living in the Age of the Imperial CEO”, 2026.10. ··· The starting point for today’s letter. It covers Meta’s 1,500% gain since IPO, Snap’s 53.1% voting stake alongside an ~70% drop from its IPO price, S&P’s 2017 ban and 2023 reversal, and Commissioner Jackson’s speech.
- Reuters (via TimesLIVE), “Who controls powerful AI? Anthropic has a plan for long after its leaders depart”, 2026.10.27. ··· The reporting detailing the scope of the 50.1% threshold, Class T of the Long-Term Benefit Trust, and controlled company status.
- ROIC.ai, “Anthropic founders to retain voting control for decades post-IPO”, 2026.10.26. ··· Source detailing the 1 Class F share structure and the “at least 3 founders” condition.
- InvestmentNews, “Meta deal shields Zuckerberg from California wealth tax bill”, 2026.10.22. ··· Source for the timing of the Class C issuance, the immediate 20% sale, and the 8-year residency commitment.
- Bloomberg Law, “Zuckerberg Stock Deal, Meta Restructuring Hit With Challenge”, 2026.10.27. ··· Covers the pension fund’s legal claims, particularly the argument that his threat to leave was a sham.
- Investinglive, “SpaceX files for Nasdaq IPO with Musk retaining 85.1% voting control”, 2026.5.20. ··· Source for Class A at 12.3%, Class B at 93.6%, and combined voting control at 85.1%.
- Martijn Cremers, Beni Lauterbach, Anete Pajuste, “The Life-Cycle of Dual Class Firm Valuations”, ECGI, 2018.11. ··· The original paper documenting the 13% premium, its disappearance in 6 to 9 years, and sunset provision proposals.
- Korea Law Information Center, “Special Act on the Promotion of Venture Businesses”, Articles 16-11 to 16-13. ··· Statutory provisions detailing issuance requirements for multiple-voting shares, conversion to common shares, and matters reserved for 1-share-1-vote rules.
Background
- Washington Technology, “SpaceX’s governance structure is built for one person: Elon Musk”, 2026.5. ··· Explains why ousting Musk is practically impossible.
- Bloomberg Government, “Snap Attracts Activist Investor Irenic in Call for Changes”, 2026.3.31. ··· Irenic’s stake and its demands.
- Paul Graham, “Founder Mode”, 2024.9. ··· The original essay that popularized the phrase “founder mode.”
- Thomas A. Stewart, “The King Is Dead”, Fortune, 1993.1.11. (Computer History Museum archives) ··· The article from over 30 years ago that declared the demise of the imperial CEO.
- Fortune, “Anthropic’s Dario Amodei says up to 40% of his time goes to company culture”, 2026. ··· Source for the quote in Oswarld's Lens where Dario Amodei mentions spending up to 40% of his time on culture.
Related Past Issues
- A $135 Rocket: Dream or Bubble? ··· Issue 120. Covered SpaceX’s valuation and demand engineering right before its IPO. Today’s letter looks at the governance side of that same listing.
- Three Ledgers Counting One Share ··· Issue 234. Covered California’s Proposition 40 and Anthropic founders’ pledge. Essential context for why Meta acted when it did.
- Middle Managers Are Disappearing? Look at What’s Really Vanishing ··· Issue 87. Explored the flattening of internal organizational hierarchies. Today’s letter looks at the flip side: power consolidating at the very top.
📝 Glossary
Footnotes
-
Servant Leadership: The perspective that a leader is not a commander directing others, but a facilitator who enables team members to do their best work. Robert Greenleaf coined the phrase in a 1970 essay, and it spread widely across startups after the official Scrum Guide described Scrum Masters as “servant leaders” prior to its 2020 edition. The 2020 revision dropped the term in favor of “true leaders who serve,” re-centering the emphasis back on leadership over subservience. ↩
-
S-1: The registration statement filed with the U.S. Securities and Exchange Commission (SEC) before a public offering. As the first disclosure of financial statements, business risks, and governance architecture, it is the most reliable window into a company prior to its IPO. ↩
-
Dual-class Shares: A capital structure where different share classes carry unequal voting rights. Typically, founders receive super-voting shares with multiple votes per share, while public investors receive 1 vote per share or non-voting shares. In South Korea, they are termed boksu uigyeolkwon (multiple-voting shares) and are restricted solely to unlisted venture companies. ↩
-
Controlled Company: A publicly listed company in which an individual or group holds a majority of the voting power for the election of directors. Major U.S. stock exchanges exempt controlled companies from several corporate governance requirements, such as maintaining a board majority of independent directors. ↩
-
Tobin’s Q: A ratio calculating a company’s market value divided by the replacement cost of its assets. A value greater than 1 indicates the market awards a premium for unbooked intangible value, such as executive leadership or growth prospects. ↩
-
Activist Investor: An investor who acquires an equity stake to publicly pressure management for operational changes, cost reductions, asset sales, or share buybacks. In dual-class companies, their leverage is constrained because prevailing in proxy contests is virtually impossible. ↩
-
Sunset Provision: A clause dictating that a specific legal right automatically expires after a designated period. In dual-class governance, it typically mandates converting founder shares to 1-share-1-vote common stock after a certain number of years, or requires public shareholders to vote on whether to extend them. ↩
Related issues
How Figma Survived AI to Become Its Workbench
Canva and Webflow entered ChatGPT, but coding agents keep turning to Figma to fetch their designs.
BusinessThe Judgment Filter Bubble: 86% of Experts Picked AI's Side
Anthropic secretly paired 50 expert analysts with an AI agent whose opinions were set by coin flips—and most followed along.
BusinessApple's Flash Suppliers Finally Send the Bill
iPhone storage costs jumped from $15 to $66, and this week's Mac price tags show exactly why.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?